
Bridge Financing · Oregon
Bridge loans in Oregon — buy before you sell
Unlock the equity in your current Oregon home so you can make a clean, non-contingent offer on your next one. Lumen Mortgage offers bridge financing statewide with closings in as few as 10 days, interest-only payments, and flexible 1–24 month terms.
- Close in 10–14 days
- Interest-only payments
- Up to 80% LTV on departing home, or 100% cross-collateralized
- No sale contingency required
What is a bridge loan in Oregon?
A bridge loan is a short-term mortgage that uses the equity in your current Oregon home to fund your next purchase — so you can buy before you sell. Most homeowners can borrow up to 80% of their current home's value, minus the existing mortgage. Payments are interest-only, loans typically close in 10–14 days, and every bridge is structured case by case around your sale timeline.
- Up to 80% LTV against your departing home's appraised value
- Up to 100% financing on the new home when cross-collateralized, case by case
- Interest-only payments during the 1–24 month bridge term
- No sale contingency — write a clean offer in competitive markets
- Loan amounts from $100,000 to $5,000,000 across Oregon
What is a bridge loan?
A bridge loan is a short-term financing tool that uses the equity in your current home to fund the purchase of your next one — so you can buy before you sell. It literally bridges the gap between two real estate transactions, giving you the buying power you need when your timing doesn't line up with the market.
Bridge loans are typically 1–24 months, interest-only, and structured to be repaid when your current home sells. They're designed for move-up buyers, downsizers, cross-state relocators, and anyone caught in a timing gap between two transactions in competitive Oregon markets like Portland, Bend, and the Willamette Valley.
The lender appraises your departing home, calculates the net equity available after your existing mortgage, and provides bridge funds up to 80% LTV. You use those funds for the down payment and closing costs on your new purchase — making a clean, non-contingent offer that puts you on equal footing with cash buyers.
For homeowners who would otherwise be forced to sell first, rent temporarily, move twice, and risk losing their target home in a bidding war, a bridge loan is often the difference between landing the right house and starting the search over from scratch.
How much can I borrow with a bridge loan in Oregon?
To estimate how much bridge capital you can access, you'll need three numbers: your current Oregon home's appraised value, your existing mortgage balance, and the target LTV (typically 80%).
Max bridge = (Home value × 80%) − Existing mortgage balance.
Use our bridge loan calculator below to model your exact scenario — including the monthly interest-only payment during the bridge term and the total cost across a 3-, 6-, or 12-month hold.
Bridge Structure
Borrow against up to 80% of your departing home's value, minus your existing mortgage.
Bridge Loan Amount
$340,000
Home value × 80% minus existing mortgage
Monthly Interest
$2,550
Interest-only at 9.00% per month
Total Bridge Interest
$15,300
Over 6 months — full cost of bridging
Alt: Temp Housing Cost
$19,200
6 mo × $3,200/mo (sell-first alternative)
Bridge Saves vs. Sell-First
$3,900
Bridge interest ($15,300) is lower than temp housing ($19,200) — plus you avoid disruption
Net home equity (value minus balance): $470,000 · Current LTV: 27.7% · Bridge uses up to 80% LTV, leaving remaining equity intact until sale.
Want a real number for your scenario?
These are estimates only. Actual bridge terms, rates, and fees depend on property appraisal, lender guidelines, and your full financial profile.
Estimates are illustrative and do not constitute a commitment to lend. Bridge loan availability, LTV limits, and rates vary by lender and borrower profile. Lumen Mortgage Corporation · NMLS #1498678 · Licensed in Oregon & California.
How to read your results: A typical Oregon bridge scenario: departing home worth $650,000 with $180,000 remaining on the mortgage. Net equity = $470,000. At 80% LTV, the maximum bridge loan is $340,000 (80% of $650K minus the existing $180K balance). That $340,000 funds the down payment on your next purchase, and the bridge is retired when the departing home sells. Contact us if you want to walk through your specific numbers.
Bridge loans for Oregon home purchases
Oregon's housing market moves fast in most metros and micro-markets — and bridge financing is built for exactly those timing pressures. Whether you're upsizing in Portland, downsizing to a condo in Ashland, or relocating from the Bay Area to Bend, the ability to make a clean, non-contingent offer is often what separates the winning bid from second place.
Portland metro move-up buyers
Portland's inventory remains tight in neighborhoods like Sellwood, Alameda, Laurelhurst, and the West Hills. Sellers routinely reject offers with sale contingencies when they can choose a competing bid without one. A bridge loan lets Portland move-up buyers access equity from their starter home to write a clean offer on their next property — then list the departing home on their own timeline, often vacant and staged, which typically commands a higher price.
Bend, Central Oregon, and cross-state relocators
Bend continues to attract buyers from California, Washington, and Colorado — many of whom are trying to coordinate a sale in one state with a purchase in another. Lumen is licensed in both Oregon and California, so we can structure the bridge financing on your departing California property and the purchase loan on your new Central Oregon home from a single lender relationship. Same dynamic applies to buyers relocating in the reverse direction from Portland, Eugene, or Ashland to coastal California or the Bay Area.
Ashland, Eugene, and Willamette Valley downsizers
Downsizing to a condo or smaller home in Ashland, Eugene, Corvallis, or Salem often triggers the same timing problem: the target property comes on market before the larger home is sold. A bridge loan lets Willamette Valley and Southern Oregon downsizers move on their schedule, then sell the departing home — usually for more — once it's empty and properly staged. University-town markets like Eugene and Corvallis also see strong bridge use from faculty and staff with fixed start dates tied to academic calendars.
What do you need to qualify for a bridge loan in Oregon?
Eligible property types
- Primary residences (owner-occupied, departing or purchase)
- Second homes and vacation properties
- Investment real estate (case-by-case)
- Single-family, 2–4 units, condos, and townhomes
Equity and LTV requirements
- Minimum 20–30% equity in departing residence
- Up to 80% LTV against departing home appraised value
- Clear exit strategy — listed or intent to list within 30–60 days
- Extensions available if sale timeline runs long
Credit and borrower requirements
- Best pricing with strong credit (740+)
- Income sufficient to carry existing + bridge + new mortgage
- Individuals and qualifying entities accepted
- No prepayment penalty on early payoff
Loan terms and structure
- Loan amounts: $100,000 – $5,000,000
- Term: 1–24 months with extension options
- Interest-only monthly payments during bridge period
- Retired by sale proceeds or refinance to permanent financing
Is a bridge loan better than a HELOC or selling first?
Oregon homeowners who need liquidity to buy before they sell have three main options: a bridge loan, a HELOC on the departing home, or selling first and buying second (often with a rent-back or temporary housing bridge). Each fits a different scenario.
| Criterion | Bridge loan | HELOC / sell-first |
|---|---|---|
| Time to close | 10–14 days | 30–45 days (HELOC) / contingent on sale |
| Home must be listed | No — plan to list within 30–60 days | No (HELOC) / Yes (sell-first) |
| Upfront purchase capital | Full lump sum | Draw over time (HELOC) / sale proceeds |
| Payment during bridge | Interest-only | Variable rate draw / temporary rent |
| Offer strength | Clean, non-contingent | Typically contingent on sale |
| Best for | Competitive-market buyers needing speed | Ongoing equity access or non-time-sensitive moves |
For Oregon investors who plan to hold and rent the next property rather than sell the first, a DSCR loan may fit better than a bridge. If your scenario involves self-employment income verification on top of the bridge, our self-employed loan programs are designed for exactly that stack.
What Oregon homeowners say about Lumen Mortgage
"From start to finish, he made the entire process feel effortless and filled us with confidence."
"David and his team over at Lumen did a fantastic job at helping us secure a loan for our ranch in a very tight timeframe. Their customer service was unmatched, and we feel so grateful to have worked with them! Thank you David and team!"
Verified Google reviews from Oregon clients.
Frequently asked questions — bridge loans in Oregon
How do bridge loans work for Oregon homeowners?
A bridge loan lets an Oregon homeowner borrow against the equity in their current home to fund the down payment on a new purchase — before the current home is sold. The lender appraises the departing property, calculates net equity after the existing mortgage, and extends a bridge loan up to 80% LTV. Monthly payments are typically interest-only during the 1–24 month bridge term. When the departing home sells, the sale proceeds pay off the bridge loan, leaving you with a single mortgage on your new home. Typical Oregon closings run 10–14 days.
How much can I borrow with a bridge loan in Oregon?
Usually up to 80% of your current home's value, minus your existing mortgage. For example, a $650,000 home with a $180,000 mortgage could support a bridge loan of about $340,000. With enough equity, we can also cross-collateralize both homes and finance up to 100% of your new purchase. Final amounts are set case by case.
How fast can a bridge loan close?
Typically 10–14 days, compared with 30–45 days for a HELOC. That speed lets you make a non-contingent offer in competitive markets.
Do I have to make monthly payments on a bridge loan?
Yes, but they're interest-only: each month you pay just the interest on the bridge balance while you own both homes. The balance is paid off from your current home's sale, with no prepayment penalty.
How much equity do I need in my Oregon home to qualify for a bridge loan?
Most bridge programs require at least 20–30% equity in your departing Oregon home after the existing mortgage. The bridge is then sized so your existing mortgage plus the bridge stays at or below 80% of the home's appraised value. For example, a home worth $600,000 with a $200,000 mortgage has $400,000 of net equity — enough to support a bridge loan up to roughly $280,000 (80% of value minus the existing balance). We calculate this precisely during pre-qualification.
What happens if my Oregon home doesn't sell during the bridge term?
Most bridge loans include extension options, and we work with Oregon borrowers proactively if the sale timeline runs long. The goal is always to get you to permanent financing — whether through sale proceeds or a long-term refinance on the new property. Extension fees are typically modest compared to the cost of letting a deal fall through or being forced into a rushed sale.
Can I use a bridge loan to move from Oregon to California (or vice versa)?
Yes — and cross-state OR/CA moves are one of the most common bridge scenarios we handle. Lumen Mortgage is licensed in both Oregon and California, so we can coordinate the bridge financing on your departing property and the purchase loan on your new home across state lines from a single lender relationship. The process works the same regardless of direction.
How are bridge loan rates priced in Oregon?
Bridge loan terms vary by lender and are structured case by case. Bridge rates run higher than a 30-year fixed mortgage, but for most borrowers who only need the funds for 1–24 months, the best structure is a higher rate with lower upfront fees — because you're paying interest for a short time, cutting fees usually saves more than chasing the lowest rate. There's no prepayment penalty, so you can pay the bridge off as soon as your home sells.
Can I carry three mortgages at once with a bridge loan?
Yes — and that's how most bridge scenarios work. During the bridge period you'll temporarily carry: (1) the existing mortgage on your departing Oregon home, (2) the interest-only bridge loan, and (3) the new mortgage on your purchase. Lenders evaluate your ability to carry all three during the bridge window. Once the departing home sells, the first two are retired and you're left with a single mortgage on the new property.
How is a bridge loan different from a HELOC?
A HELOC is a revolving line of credit against your current home that you control and draw from over time — useful for ongoing equity access but slower to set up (30–45 days) and often capped below what you'd need for a full down payment. A bridge loan is a short-term, lump-sum loan specifically structured to fund the gap between buying and selling. It closes in 10–14 days, provides full purchase capital upfront, and is designed to be retired when the current home sells.
Can I use a bridge loan for an Oregon second home or investment property?
Yes. Bridge loans are most common for primary residence move-ups, but we also structure bridges for second-home purchases and, on a case-by-case basis, investment properties — particularly when an Oregon investor wants to move quickly on a rental acquisition and plans to refinance into a DSCR loan once the property stabilizes. Contact us to discuss the specific scenario.
Further reading on bridge loans
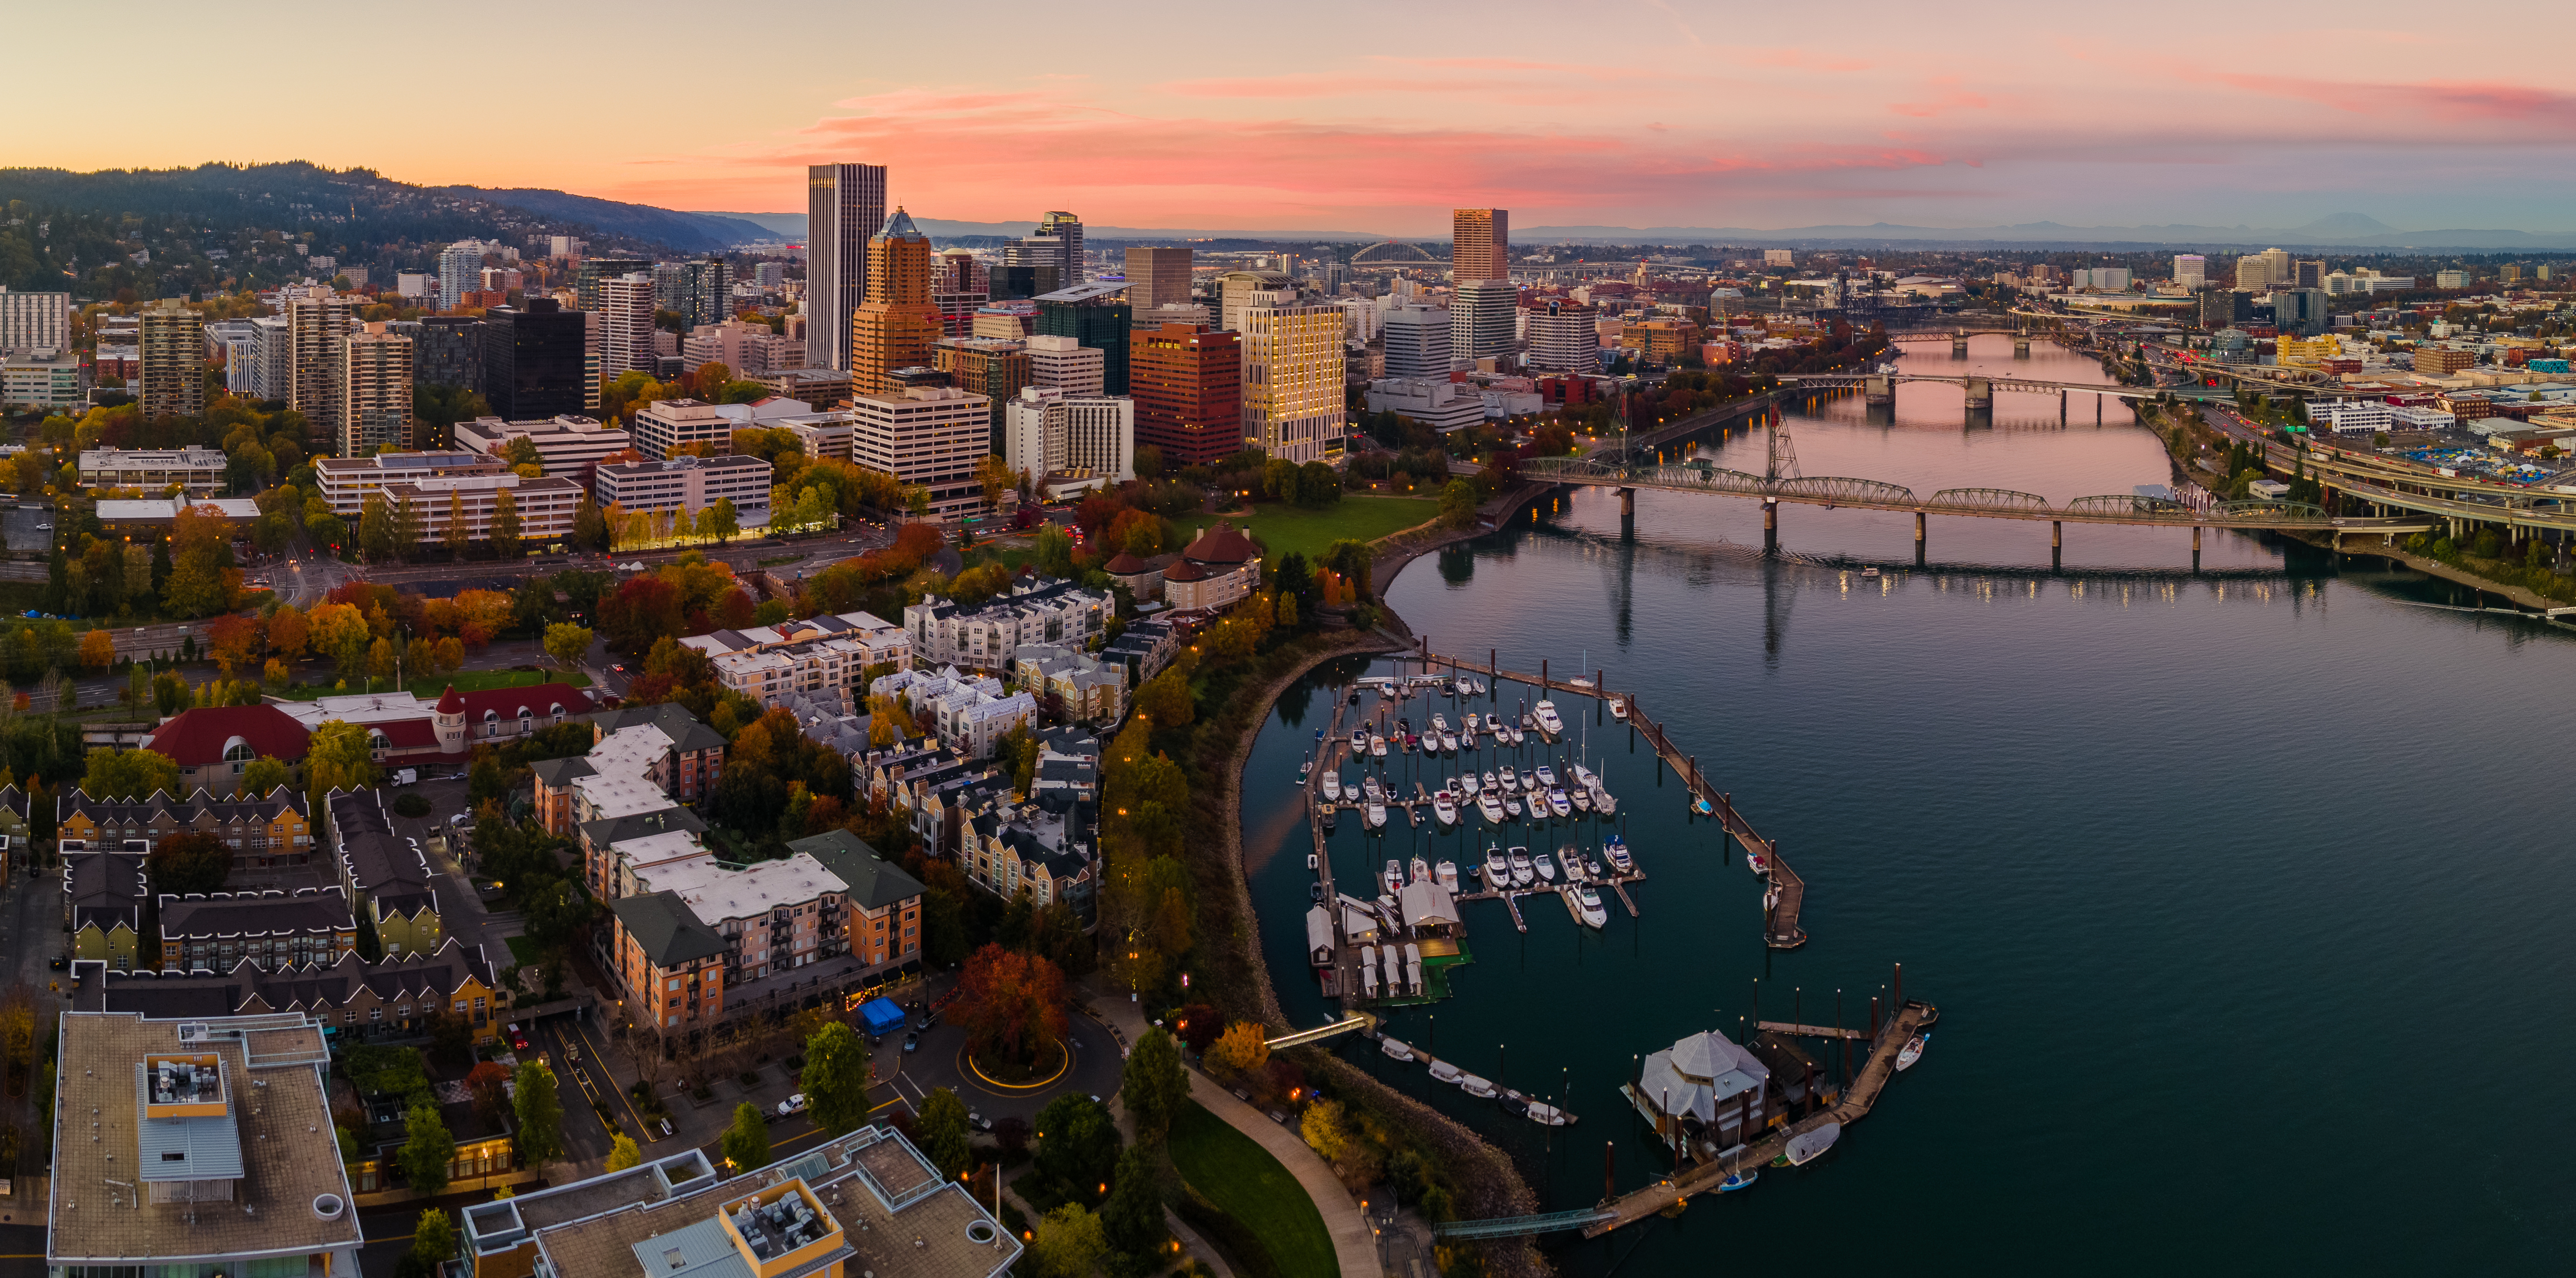
How Bridge Financing Works in Oregon: Traditional Bridge vs. HELOC vs. Buy-Before-You-Sell
Selling a home and buying another one at the same time is one of the most logistically complicated things most people do in their financial lives. Bridge financing gives you access to the equity in your current home before the sale closes, so you can act like a non-contingent buyer on your next purchase, move on your own timeline, and stop choosing between two impossible sequences.
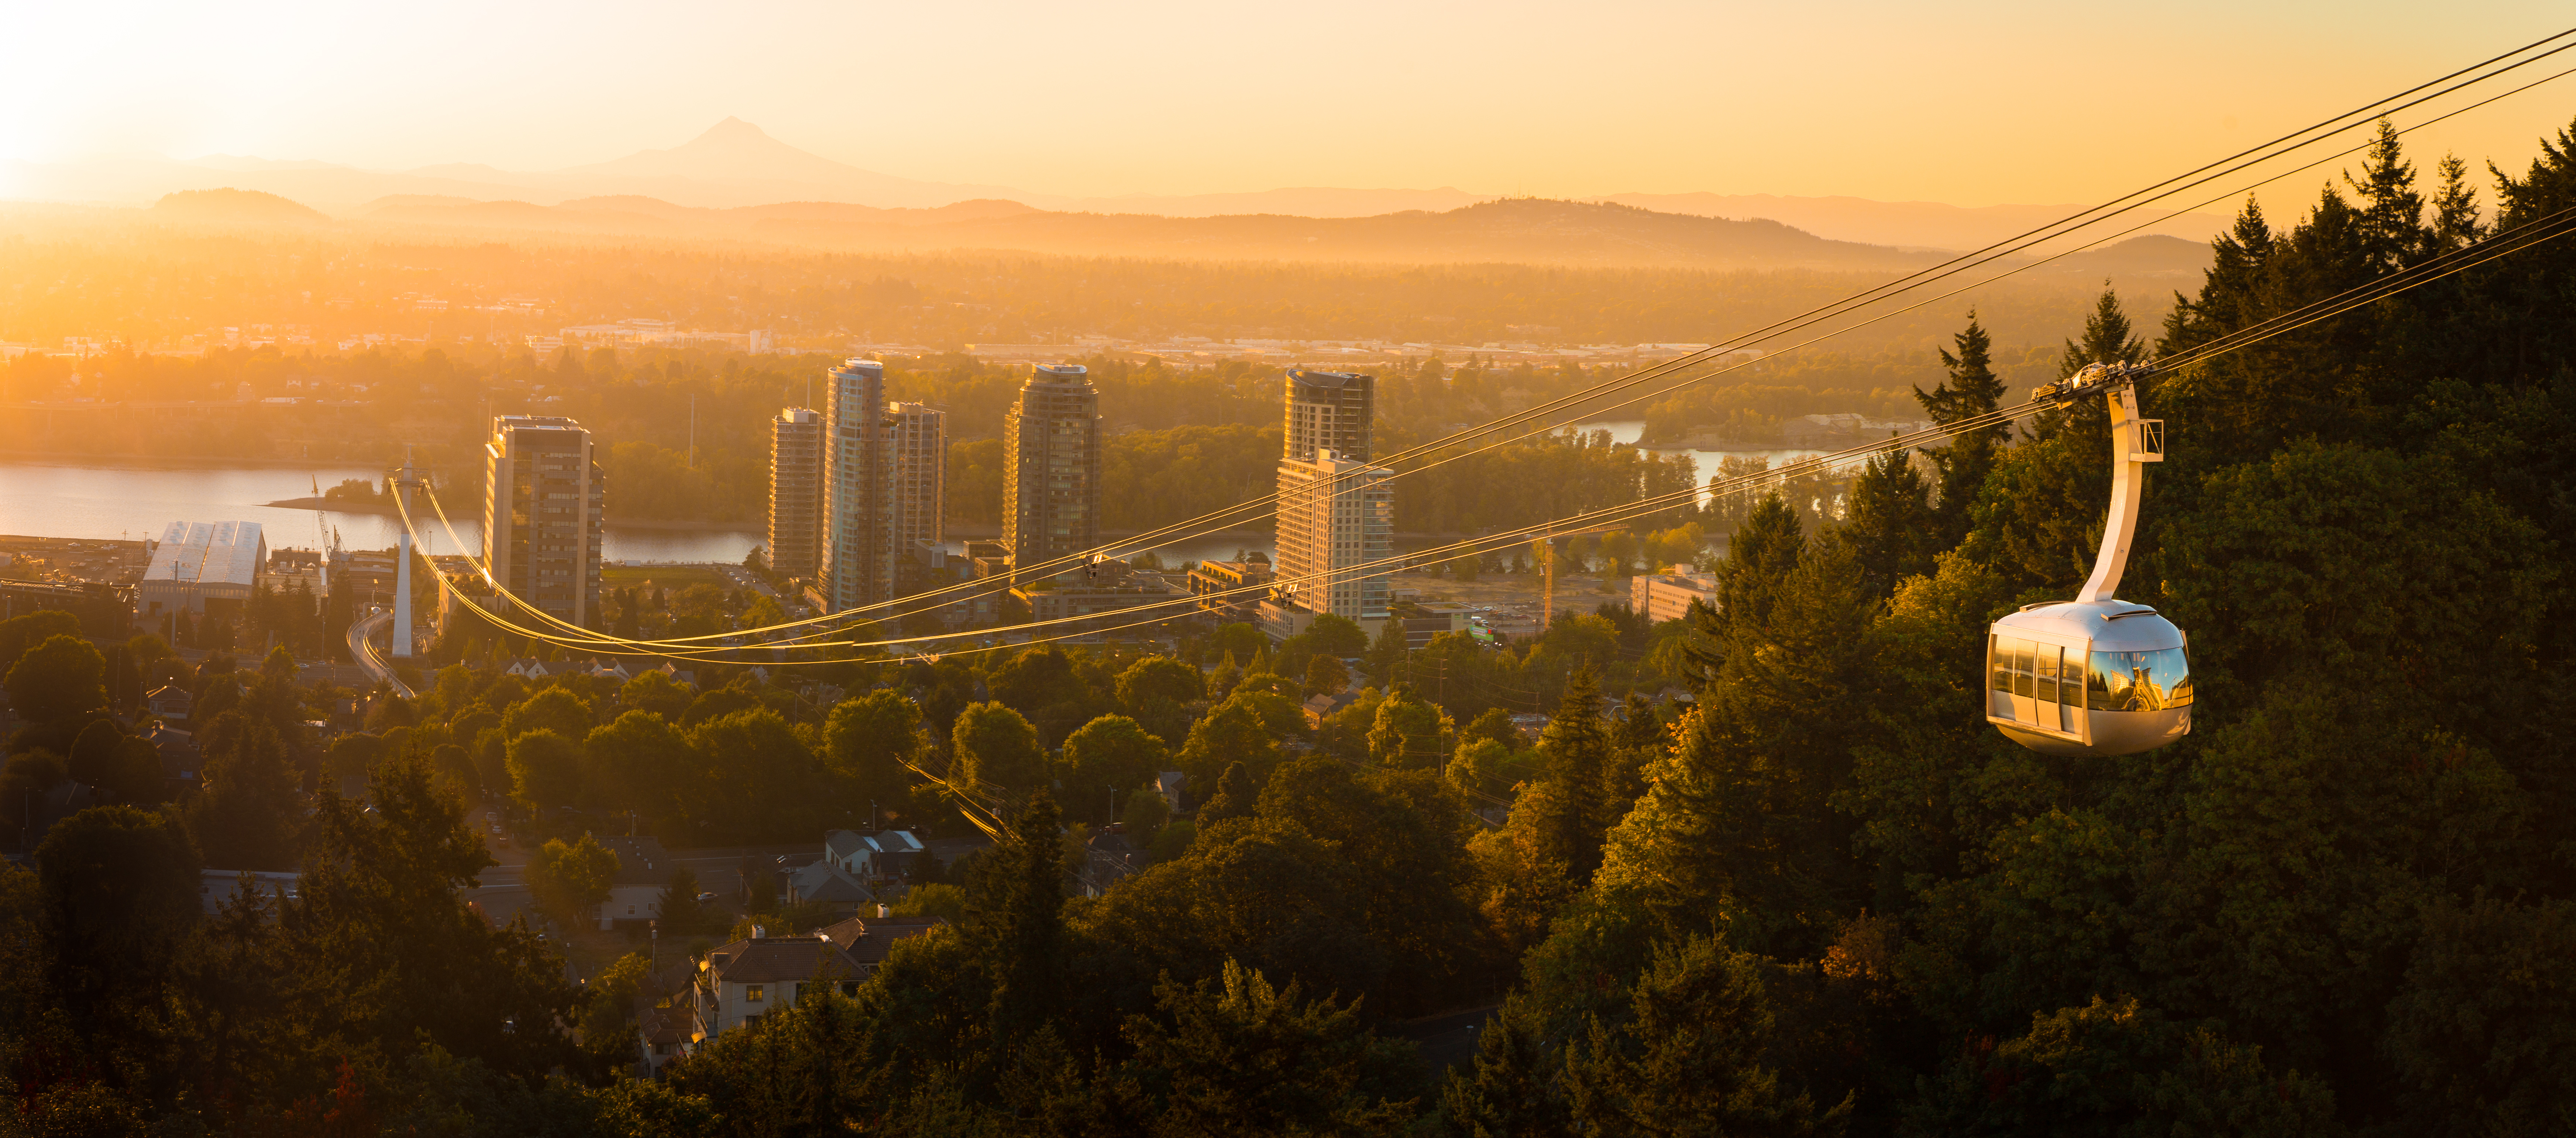
Bridge Loans in Portland's Competitive Housing Market: How to Win Without a Sale Contingency
Portland's tightest neighborhoods move fast -- a well-priced listing in Sellwood, Alberta, or Lake Oswego can draw multiple offers within days. A bridge loan turns your existing equity into instant buying power, letting you write a clean offer that stands out in a field of contingent buyers.
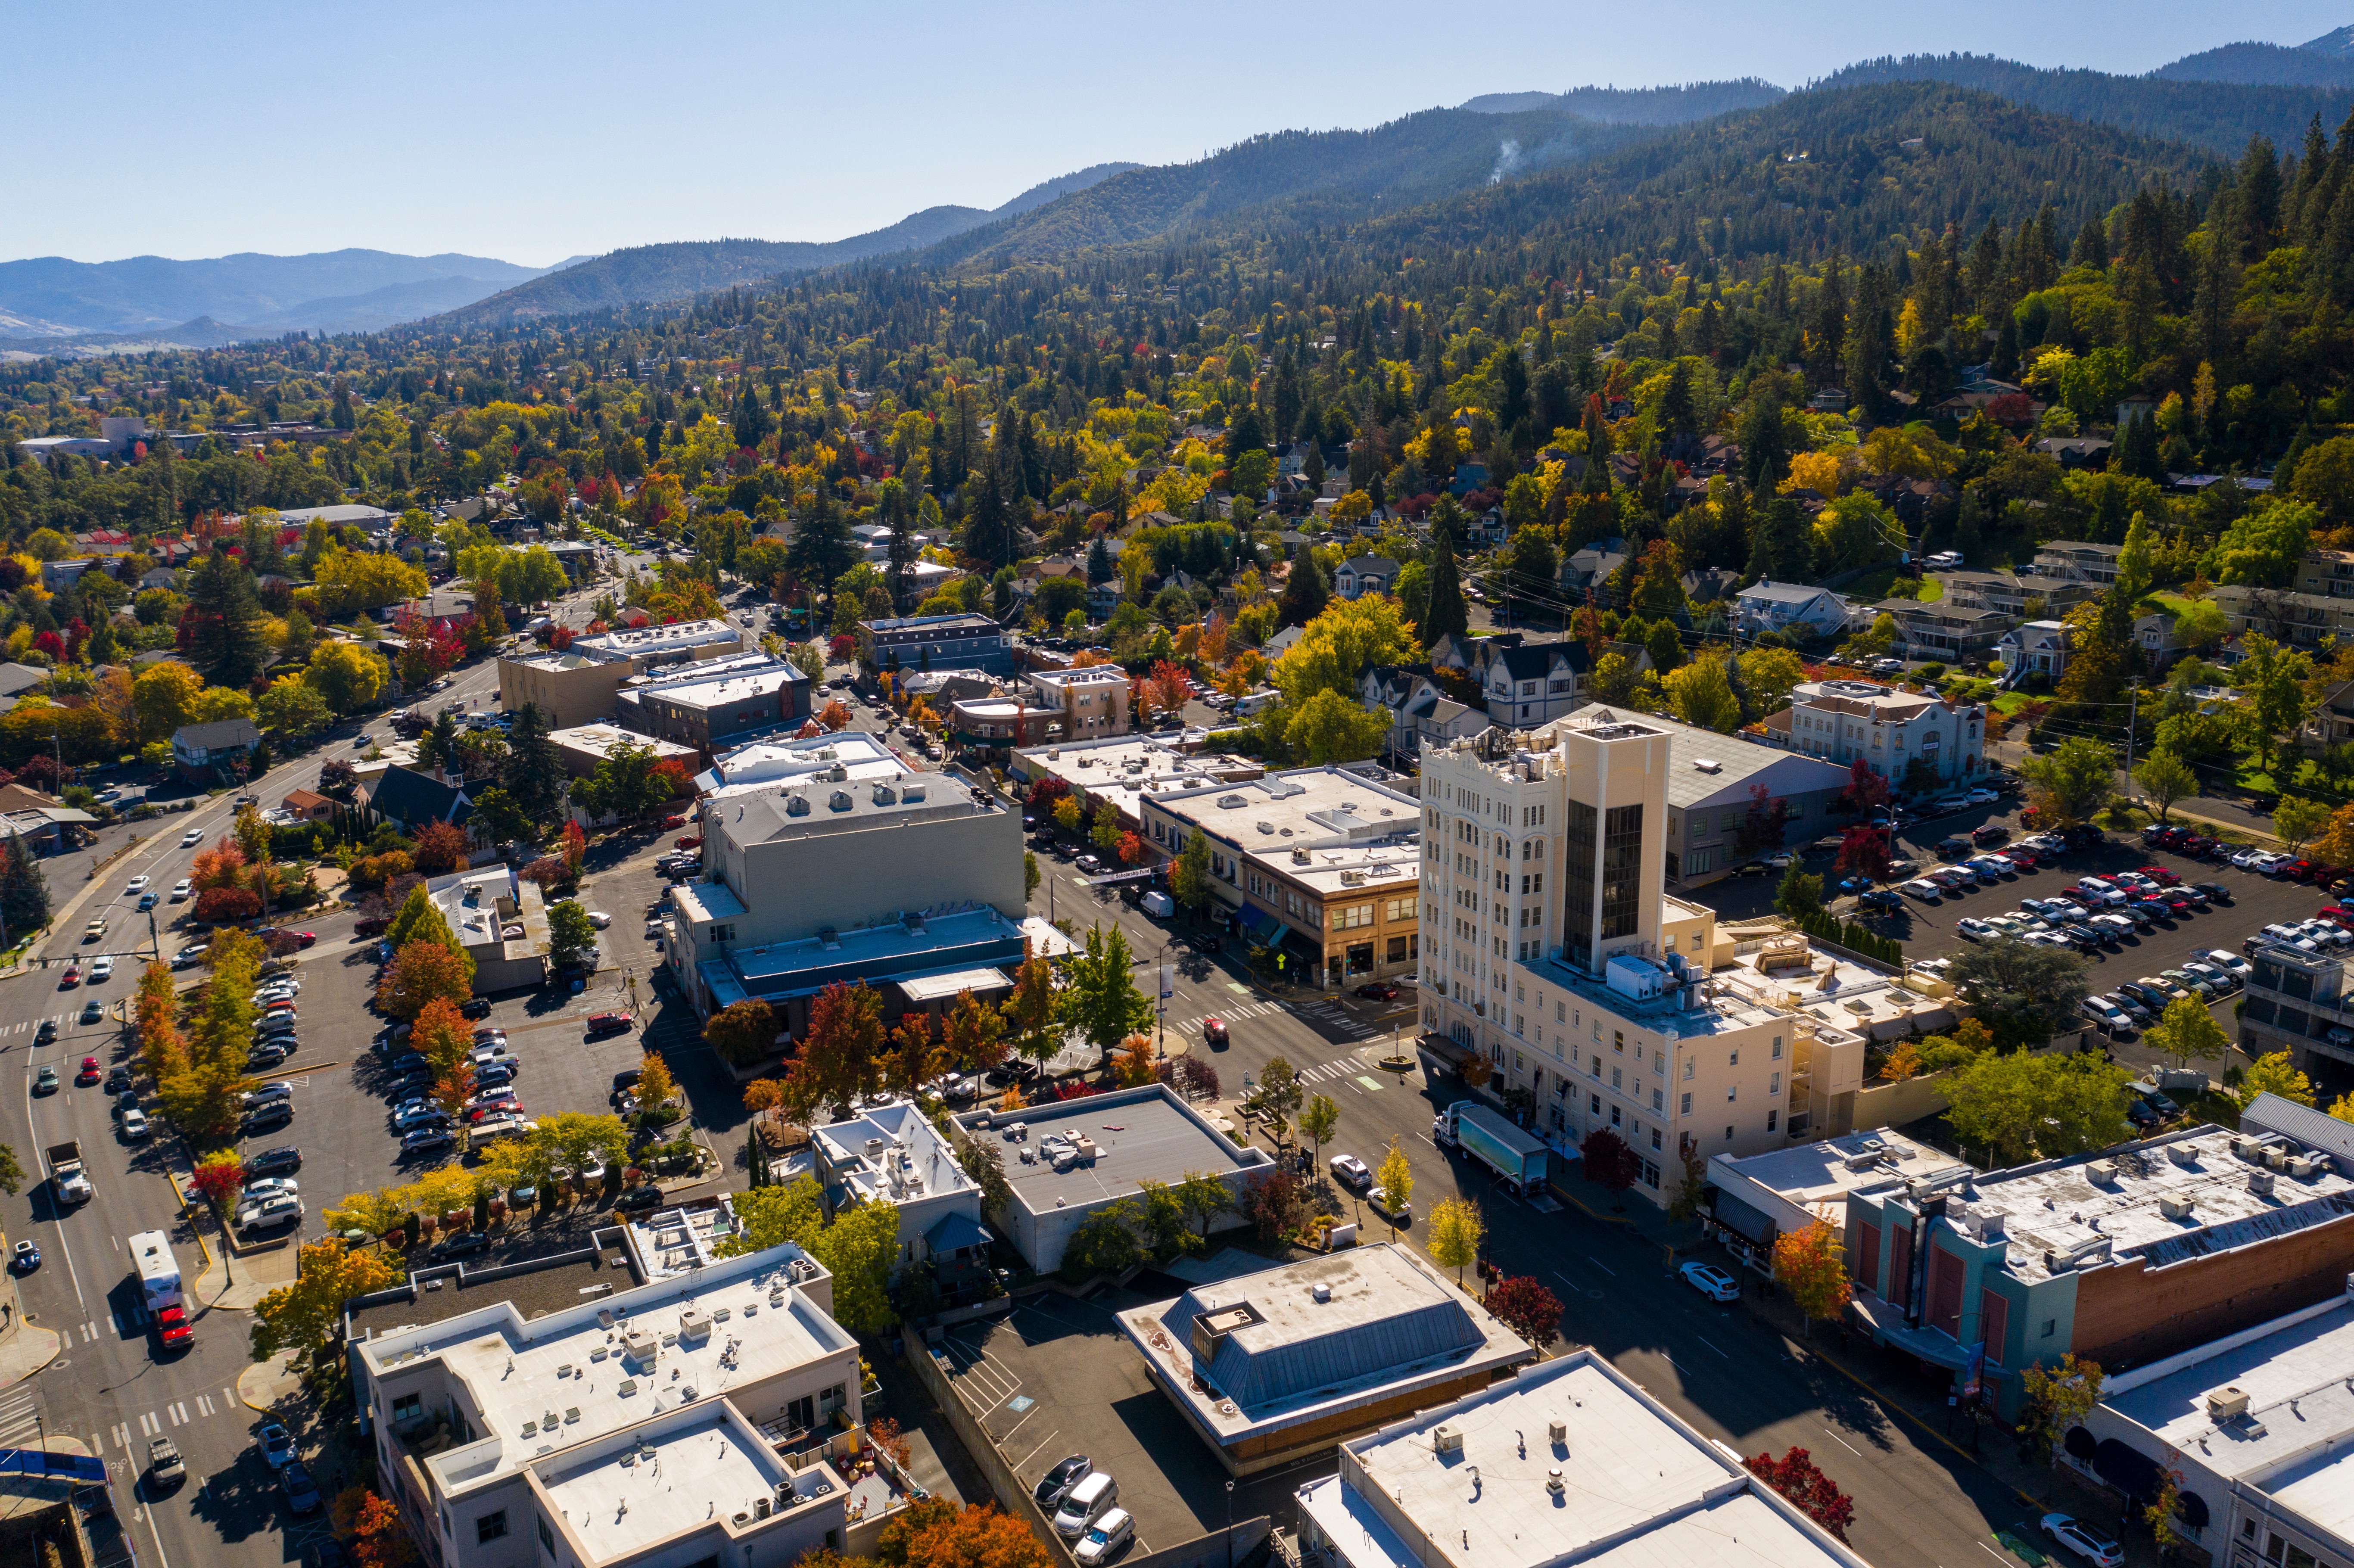
Bridge Loans in Ashland, Oregon: How to Buy a Condo Before Selling Your Home
Ashland's condo inventory is small and moves fast -- especially walkable units near the Plaza, Lithia Park, and the Oregon Shakespeare Festival. A bridge loan lets you lock in the right condo now and sell your single-family home on your own terms, without temporary housing or contingencies.
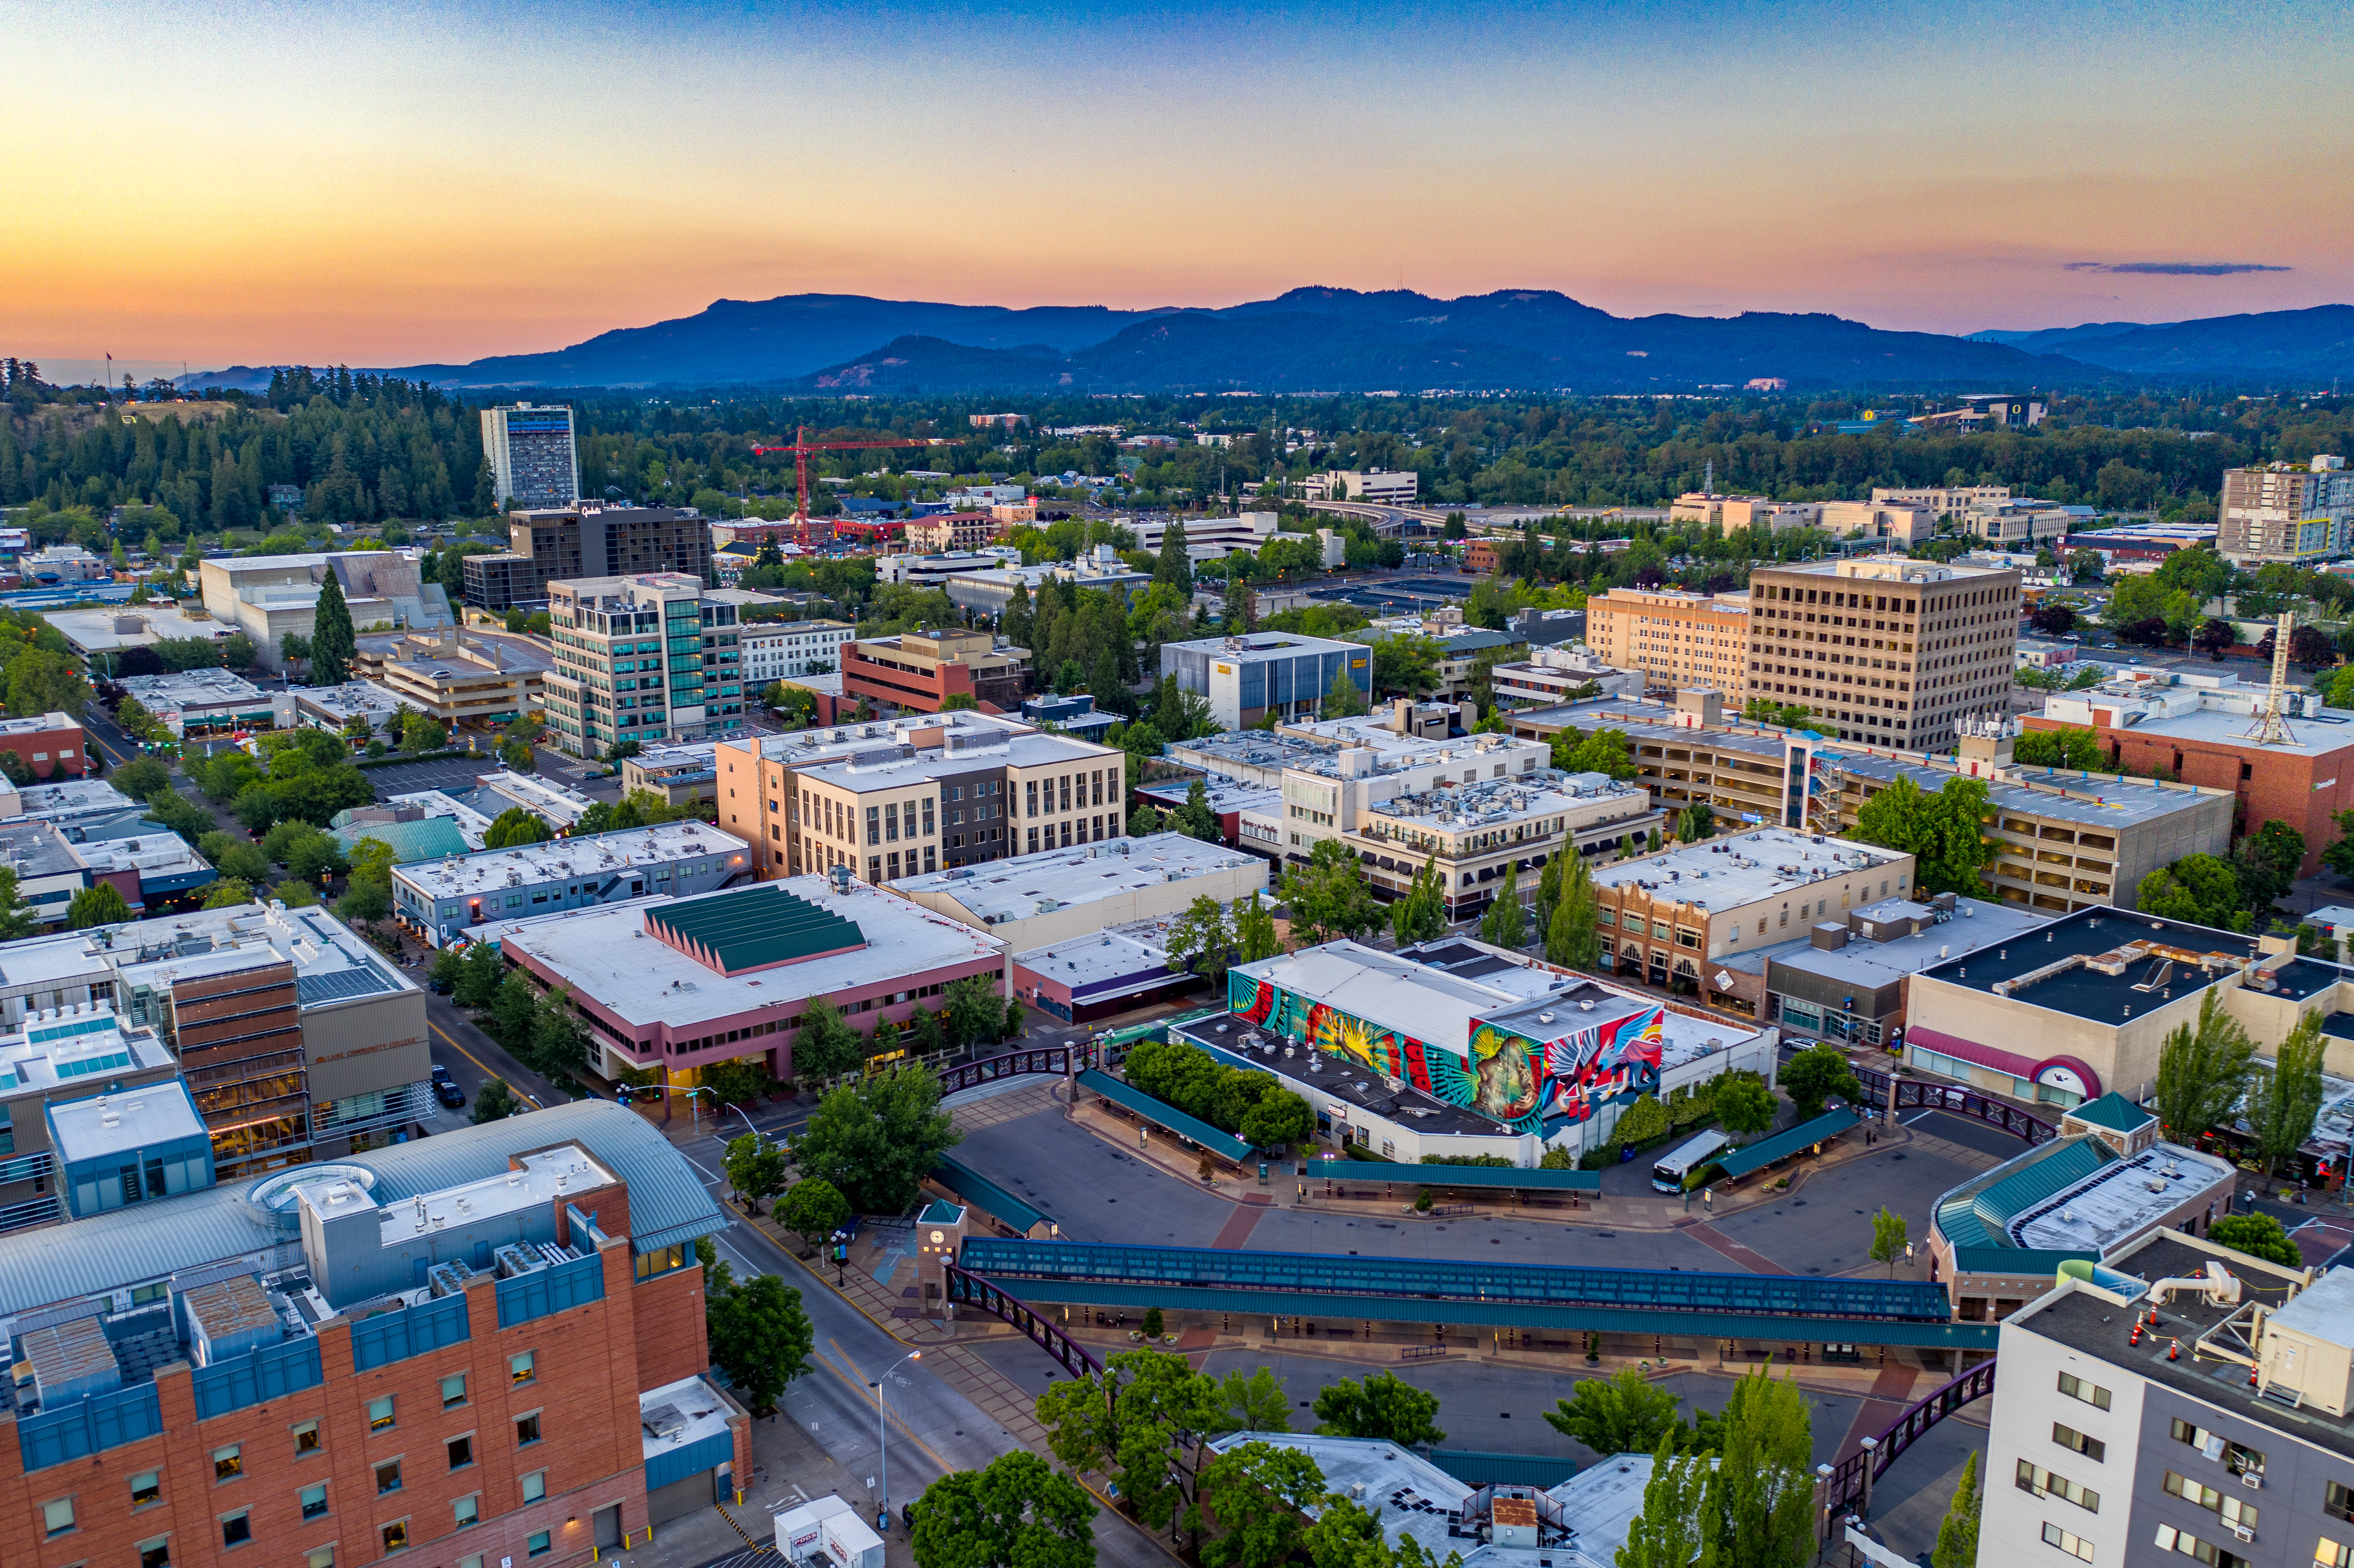
Bridge Loans in Eugene, Oregon: How to Win Your Next Home in a University Town Market
Eugene's best neighborhoods -- South Hills, Fairmount, Amazon, and the College Hill corridor -- move fast when priced right. A bridge loan lets you make a clean offer using your existing equity, so you don't lose your target home while waiting for your current one to sell.
Explore related loan programs
Ready to talk to a Oregon loan officer?
We'll walk you through the numbers, explain your options, and let you decide — no pressure, no sales pitch.