What is delayed financing?
Delayed financing lets you buy a home with cash and then take out a mortgage on it shortly after closing to put that cash back into your accounts. You get the negotiating power of an all-cash offer, then end up with a normal mortgage. With Lumen Mortgage's portfolio delayed financing, the loan is not hit with the cash-out pricing adjustments that conventional loans apply, so you can get the same terms you would have had on a regular purchase loan. The key is getting pre-approved for the delayed-financing loan before you write the offer, so you know the cash is coming back.
Best for: Buyers with enough liquid or investment assets to close in cash who are competing for a hot listing or a specific property in Oregon or California
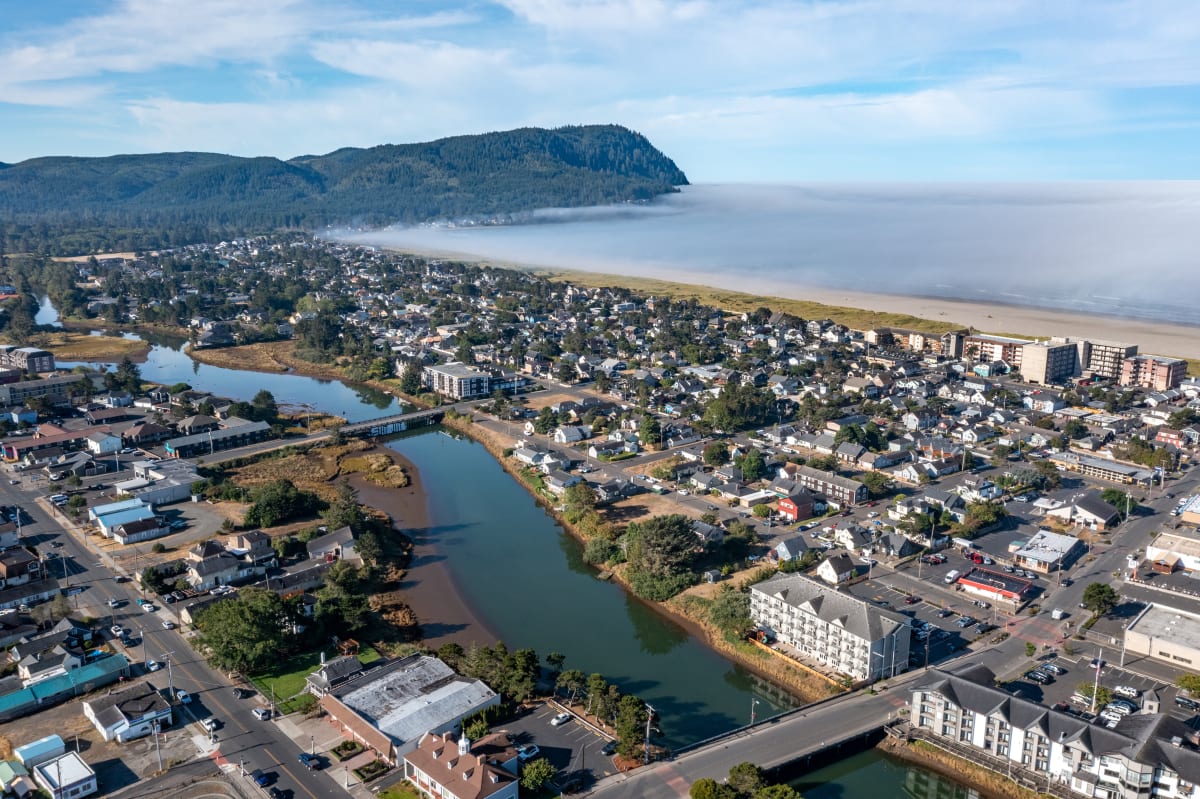
Some houses don't go to the highest bidder. They go to the cleanest offer — and in a multiple-offer situation, nothing is cleaner than cash. No financing contingency, no appraisal contingency, a short close. Sellers love it, and listing agents often steer their clients toward it even when a financed offer is slightly higher. That was exactly the situation for longtime clients of ours who found a second home in Seaside, Oregon. It was a hot property, and their agent believed only a cash offer would win it. They had the money — but it was sitting in investment accounts they had no intention of leaving drained. So we planned it out together: buy with cash, then replace that cash with a mortgage right after closing. This is called delayed financing. They won the house, and we closed their loan three weeks later, on the same terms they would have gotten with a regular purchase loan. We qualified them on their assets, so they skipped the full income and employment paperwork — and their terms beat what a conventional loan would have offered. Here's how delayed financing works, why getting pre-approved before the cash offer matters so much, and the details that make the difference between a smooth refinance and a frustrating one.
How Delayed Financing Works
Delayed financing is a refinance done shortly after an all-cash purchase. The sequence is simple: 1. Get pre-approved for the delayed-financing loan before you write the offer. 2. Buy the home with cash. Your offer has no financing contingency, which is what makes it competitive. 3. Close the purchase and record the deed in your name. 4. Close the mortgage on the home you now own, usually within a few weeks. 5. Put the cash back into the accounts it came from. The end result looks a lot like a regular purchase: you own the home with a mortgage on it. The difference is that during the bidding war, the seller only ever saw a cash buyer. When the home was bought for cash recently, the loan is based on the purchase and the documented funds you used, not on a long ownership history. That is why the timeline can be so short. In Seaside, we closed the loan three weeks after the purchase.
The Seaside Second Home: What We Did
Our clients had worked with us before, so we already knew their file. When the Seaside listing came up, the plan came together quickly: Before the offer: we pre-approved them for the delayed-financing loan on the second home, so they knew the loan amount, the terms, and that the cash would come back. We also talked through which accounts to pull the purchase money from (more on that below). The offer: their agent wrote an all-cash offer with no financing contingency. It won. After closing: we ordered the appraisal, finished the file, and closed the mortgage three weeks after they bought the house. The loan proceeds went back into their accounts. How they qualified: we qualified them on their assets, not their tax returns. That meant no full income and employment paperwork — less paperwork and a faster close. The terms: because this was portfolio financing, there were no cash-out pricing adjustments. They got the same terms they would have had on a regular purchase loan, and those terms beat what a conventional loan would have offered for the same scenario.
Why You Need to Be Pre-Approved Before You Write the Cash Check
This is the most important part of the whole strategy. Delayed financing only works well when the mortgage is lined up before the cash goes out. If you buy first and look for the loan afterward, you might find out the property doesn't fit the program, the appraisal comes in low, the account you pulled from creates a documentation problem, or the loan amount is smaller than you expected. At that point the cash is already spent, and you've lost your leverage. Getting pre-approved first means you can write the cash offer with confidence. Before you commit the money, you'll know: - How much you can get back, based on the property type and occupancy. - Your terms — rate, loan term, and payment. - What documentation we need, including how to show where the cash came from. - Whether the property itself works — condition, zoning, acreage, condo questions, or anything else that could slow the loan down. - Your timeline, so you can plan when the money returns to your accounts. Pre-approval also helps your agent. You can still present a clean cash offer, while knowing your long-term financing is already planned.
No Cash-Out Pricing Adjustments With Our Portfolio Financing
On a conventional loan, taking cash out usually costs more. Conventional pricing adds cash-out adjustments (often called loan-level price adjustments), which can mean a higher rate or more cost at closing compared with a purchase loan. Conventional delayed financing also comes with its own set of rules and limits. Our portfolio delayed financing does not apply cash-out pricing adjustments. If you bought with cash and are simply replacing that cash, we price it like the purchase it really was. That's how our Seaside clients ended up with the same terms they would have had if they had financed the purchase from the start. Our cash-out limits are up to 80% LTV and 90% CLTV on a primary residence, 85% CLTV on a second home, and 75% LTV on an investment property. CLTV (combined loan-to-value) counts any second lien, like a HELOC, along with the first mortgage. Final loan amounts depend on the appraisal, the property, and the full file.
| Occupancy | Maximum cash-out | Cash-out pricing adjustment |
|---|---|---|
| Primary residence | 80% LTV / 90% CLTV | None on portfolio financing |
| Second home | 85% CLTV | None on portfolio financing |
| Investment property | 75% LTV | None on portfolio financing |
Qualifying on Assets Instead of Income Paperwork
Many cash buyers are people whose wealth is in investments rather than a W-2 paycheck: business owners, retirees, people with stock compensation, or anyone whose tax returns don't tell the whole story. For those borrowers, we can often qualify the loan on assets. Instead of collecting two years of tax returns and verifying employment, we look at the accounts you hold and turn them into qualifying income. Our Seaside clients qualified this way and skipped the full income and employment paperwork. If you want to see how your assets might translate into qualifying income, try our assets-as-income calculator or read more about asset depletion loans.
Working With Your Financial Advisor and CPA
Where the cash comes from matters. Selling stocks can trigger capital gains. Pulling from a retirement account can create taxes and penalties. Using a securities-backed line of credit has its own costs and risks. Some accounts are simply easier to document than others. We work with our borrowers' financial advisors and CPAs regularly to make sure the structure and the accounts they're pulling from are the most beneficial from a wealth and tax strategy. Before the offer, we can get on a call together and walk through: - Which accounts to use for the purchase and how quickly each one can be accessed. - How the money will be documented, so the paper trail is clean for the delayed-financing loan. - Where the loan proceeds should go when they come back. - Timing, so sales, transfers, and the closing happen in the right order. We don't give tax advice, and your CPA has the final word on tax treatment. But coordinating early means the mortgage, the investment plan, and the tax plan all point in the same direction. If you don't have a CPA or advisor yet, visit our partners page — we're happy to make a personal introduction to a trusted professional.
Details That Keep Delayed Financing Smooth
A few practical points we cover with every delayed-financing borrower: - Keep the paper trail clean. Use funds you can document from statements. Avoid moving money between several accounts right before closing. - Plan for the appraisal. Your loan amount is based on the home's value and the purchase price. A pre-approval helps you know what to expect. - Title in your own name (or a planned entity). Tell us up front if you want to buy in an LLC or trust, so we can structure the loan correctly. - Don't wait too long. Delayed financing works best soon after the purchase. If too much time passes, it becomes a standard cash-out refinance. - Mind the payoff of any short-term funding. If you used a securities-backed line or similar borrowing for the purchase, we'll plan the loan proceeds to pay it off. To see how the new loan compares with your other options, run the numbers in our refinance calculator.
When Delayed Financing Makes Sense
Whether you're competing in a hot market or going after one specific property, delayed financing can help you win the bid and still end up with the financing terms you want. It's a strong fit when: - You're in a multiple-offer situation and the listing agent is signaling that cash wins. - The seller needs certainty or speed, such as an estate sale, a relocation, or a seller buying their own next home. - You've found a one-of-a-kind property, like a coastal second home, acreage, or a home in a tight neighborhood, and don't want to lose it to a cash buyer. - You have the liquidity but don't want it tied up in real estate long term. It's not right for everyone. If you don't have enough cash to close without the loan, a bridge loan or a standard financed offer may be the better tool. We'll tell you honestly which approach fits.
Run the Refinance Math
Refinance Savings Calculator
The decision to refinance lives or dies on three numbers: your monthly savings, your break-even point, and how long you plan to stay in the home. A lower rate is only half the answer — the other half is what it costs to get there. Closing costs, prepaid interest, and the time needed to recover them determine whether a refinance is genuinely accretive or just a transfer of future savings to upfront costs.
The blended rate calculator lets you enter your current loan balance, rate, and remaining term alongside your proposed refinance terms to see your exact monthly delta, your break-even month, and your total lifetime interest savings. Run multiple scenarios before you call a lender — so when the conversation starts, you already know what the right deal looks like.
Monthly payment delta
See exactly how much your payment changes — and whether the difference meaningfully moves your monthly budget.
Break-even timeline
Divide closing costs by monthly savings to find the month when the refinance starts actually saving you money.
Lifetime interest savings
Quantify the full value of a lower rate over your remaining loan term — the number that justifies (or doesn't) the decision.
Free · No login · No credit pull required
CPA / Tax Pro Referral
Paying cash with investment funds? Loop in a CPA first.
Which accounts you sell or borrow against to fund a cash purchase can change your tax bill. We regularly coordinate with borrowers' CPAs and financial advisors before the offer so the purchase, the delayed-financing loan, and the tax plan line up. Ask for a personal intro.
No directory. No paid placements. No RESPA-restricted referral fees. We've worked alongside these pros on real Oregon and California deals — we'll make a personal email introduction so you can interview them yourself.
Or email us directly:
Frequently Asked Questions
What is delayed financing?
Should I get pre-approved before making a cash offer if I plan to use delayed financing?
Does delayed financing cost more than a purchase loan?
How much cash can I get back with delayed financing or a cash-out refinance?
Do I need tax returns to qualify for delayed financing?
Which accounts should I use to pay cash for a home?
Is Now the Right Time to Refinance?
We'll show you your break-even point, monthly savings, and lifetime interest reduction — so you can decide with real numbers.
Bottom Line
Delayed financing lets you compete like a cash buyer and still end up with the mortgage you wanted. Our Seaside clients won a hot second home with an all-cash offer and closed their loan three weeks later — on the same terms as a regular purchase loan, qualified on their assets, with no cash-out pricing adjustments. The key is doing it in the right order: get pre-approved for the delayed-financing loan first, decide with your advisor and CPA which accounts to use, and then write the cash offer with confidence. If you're looking at a competitive listing or a specific property in Oregon or California, call 503-966-9255 or email info@lumenmortgage.com. We'll pre-approve the delayed-financing loan before you commit a dollar, and we're happy to get your financial advisor and CPA on the call. Explore our portfolio loans, refinance options, and second home financing. NMLS #1498678.