Assets as Income Calculator
Turn savings, investments, and retirement accounts into qualifying income — and compare our 36-month and 60-month portfolio programs against the Fannie Mae employment-related assets calculation side by side.
Get Started in 3 Steps
How to Use the Assets as Income Calculator
Enter Your Assets
Add your liquid, investment, and retirement balances, and flag whether the retirement-account owner is of retirement age (59½+). Add any other monthly income to include it in every result.
Set Fannie Mae Options
Open the Fannie Mae settings to choose the loan term (30- or 15-year), enter the funds needed for down payment, closing, and reserves, and flag whether the asset owner is 62 or older.
Compare the Methods
Review qualifying monthly and annual income for the 36-month program, 60-month program, Fannie Mae and Freddie Mac side by side, then request a personalized review to see which program fits your file.
Assets as Income Calculator
Portfolio programs vs. Fannie Mae and Freddie Mac
Your assets
In the 36-month program, only retirement/IRA assets use the 36-month divisor — counted at 100% if of retirement age, 90% if not — while liquid and investment assets deplete over 60 months. This toggle also removes the early-withdrawal penalty in the Fannie Mae and Freddie Mac calcs.
Qualifying income by method
Lumen 36-Month Program
Best resultPortfolio · retirement ÷ 36, other ÷ 60
$18,333/mo
Qualifying monthly income
$500,000 retirement × 90% = $450,000 ÷ 36 + $350,000 liquid/investment ÷ 60
Lumen 60-Month Program
2nd highestPortfolio · assets ÷ 60
$14,167/mo
Qualifying monthly income
$850,000 ÷ 60
Fannie Mae
4th highestEmployment-related assets
$1,111/mo
Qualifying monthly income
($500,000 retirement − $50,000 penalty − $50,000 closing) ÷ 360
Freddie Mac
3rd highestAccumulated assets · updated for Bulletin 2026-10
$4,167/mo
Qualifying monthly income
($850,000 − $50,000 penalty − $50,000 closing) ÷ 180
Want a lender-ready version of these numbers?
Send us your results and we'll review your asset mix and show which program fits your purchase. Your numbers carry over automatically.
Or call 503-966-9255
This is an estimate, not a commitment to lend or an approval. The Fannie Mae figures follow the Employment-Related Assets as Qualifying Income method and use only the retirement balance entered: eligible assets, less any early-distribution penalty and less funds needed for down payment, closing costs, and reserves, divided by the loan term in months. Fannie Mae limits eligible assets (checking and savings generally do not count unless sourced from an eligible employment-related asset; stock options, non-vested stock, inheritance, lawsuit and real-estate-sale proceeds, and virtual currency are excluded) and is available only on purchase and limited cash-out refinances of a primary residence or second home, at 70% LTV (80% if the asset owner is 62+ at closing). The Freddie Mac figures follow Bulletin 2026-10 (required for settlements on or after February 3, 2027; lenders may adopt it sooner): net eligible depository, securities and retirement assets, less any early-distribution penalty and funds needed at closing, divided by 180, with a $30,000 minimum. It requires a Loan Product Advisor Accept, a purchase or no-cash-out refinance, and 12-month seasoning on depository and securities accounts (balance changes over 20% are limited or excluded); all occupancy types are allowed and there is no age requirement. Our 36-month and 60-month portfolio programs use their own eligibility rules, and final qualifying income is determined by the underwriter after a full review. Actual results depend on program guidelines, credit, LTV, reserves, property type, and pricing. Lumen Mortgage · NMLS #1498678 · Licensed in Oregon & California. Equal Housing Lender.
How do you calculate income from assets for a mortgage?
Asset-based (asset depletion) lending converts your liquid, investment, and retirement balances into monthly qualifying income by dividing them over a set number of months. Our 36-month portfolio program divides retirement assets by 36 (counted at 100% if you're of retirement age, 90% if not) and liquid and investment assets by 60, then adds the two; our 60-month program divides total assets by 60; Freddie Mac (Bulletin 2026-10) divides net eligible assets by 180; and the Fannie Mae Employment-Related Assets method divides net eligible retirement assets — after any early-withdrawal penalty and funds needed for down payment, closing, and reserves — by the loan term in months.
Best for: Retirees, high-net-worth borrowers, and business owners between ventures who are asset-rich but income-light
How It Works
Understanding the Assets as Income Calculator
Some borrowers have substantial assets but little documentable monthly income — retirees, business owners between ventures, and high-net-worth clients whose wealth sits in savings and investments. Asset-based lending, sometimes called asset depletion, converts those balances into qualifying income so they can still be counted. This calculator compares four methods on the same assets so you can see the difference instantly.
Our 36-month portfolio program divides retirement accounts by 36, counted at 100% if the owner is of retirement age (59½+) and 90% if not, and divides liquid and investment assets by 60, then adds the two — this usually produces the highest figure. For example, $500,000 in retirement at 90% is $450,000 ÷ 36 = $12,500, plus $350,000 liquid/investment ÷ 60 = $5,833, for $18,333 a month. Our 60-month portfolio program divides total assets by 60. The Fannie Mae Employment-Related Assets method is more conservative: it subtracts any early-distribution penalty and the funds needed for your down payment, closing costs, and reserves, then divides what's left by the loan term in months (360 for a 30-year loan, 180 for a 15-year). It counts only eligible employment-related assets such as retirement accounts, and caps LTV at 70%, or 80% if the asset owner is 62 or older at closing. Freddie Mac's updated accumulated-assets method (Bulletin 2026-10, required for settlements on or after February 3, 2027) divides net eligible depository, securities and retirement assets by 180 instead of 240, requires at least $30,000 in net eligible assets, drops the age requirement on depository and securities accounts, and allows primary residences, second homes and investment properties on purchases and no-cash-out refinances.
Enter your liquid, investment, and retirement balances, flag whether the retirement-account owner is of retirement age, and optionally add other monthly income. Open the Fannie Mae and Freddie Mac settings to set the loan term, the funds needed at closing, and the age-62 flag. Because programs differ, pair this with our DTI calculator to see how the income supports a payment, then request a personalized review — final qualifying income is always set by the underwriter.
Ready to apply?
Numbers look right? Explore our Asset Depletion Loans page for eligibility details, rates, and next steps.
About This Calculator
What the Assets as Income Calculator is For
Asset-rich, income-light borrowers — retirees, business owners between ventures, and high-net-worth clients — often can't qualify on paystubs alone, even with substantial savings. Asset-based (asset depletion) lending solves that by converting your liquid, investment, and retirement balances into monthly qualifying income. This calculator compares four methods on the same assets: our 36-month portfolio program (retirement ÷ 36, counted at 100% if you're of retirement age or 90% if not, plus liquid and investment assets ÷ 60), Freddie Mac's updated accumulated-assets method (net eligible assets ÷ 180), our 60-month portfolio program (total assets ÷ 60), and the Fannie Mae Employment-Related Assets method (net eligible assets, less any early-distribution penalty and funds needed for down payment, closing, and reserves, divided by the loan term). Enter your balances to see qualifying monthly and annual income for each, plus the Fannie Mae max LTV.
Common Use Cases
- Retirees and asset-rich borrowers estimating qualifying income without employment
- Comparing portfolio asset-depletion programs against the Fannie Mae calculation
- Business owners between ventures using savings and investments to qualify
Ready to turn numbers into a loan?
Or call 503-966-9255Common Questions
Assets as Income Calculator — Frequently Asked Questions
Keep Exploring
Related Calculators
Debt-to-Income Calculator
Calculate your front-end housing ratio and back-end total DTI using gross income and all monthly obligations
Mortgage Calculator
Estimate your monthly principal & interest payment, compare 15- vs. 30-year terms, and see total interest paid over the life of the loan
Bank Statement Income Calculator
Estimate qualifying income for self-employed borrowers using 12 or 24 months of bank deposits
Conventional & PMI Calculator
Calculate your conventional loan payment with FICO-score-based PMI rates, see exactly when PMI cancels under the Homeowners Protection Act, and find out how much you'd save by improving your credit score before applying.
From the Blog
Further Reading
 Retirement
Pasadena Retirees Downsize: Buying Before Selling With Assets as Income
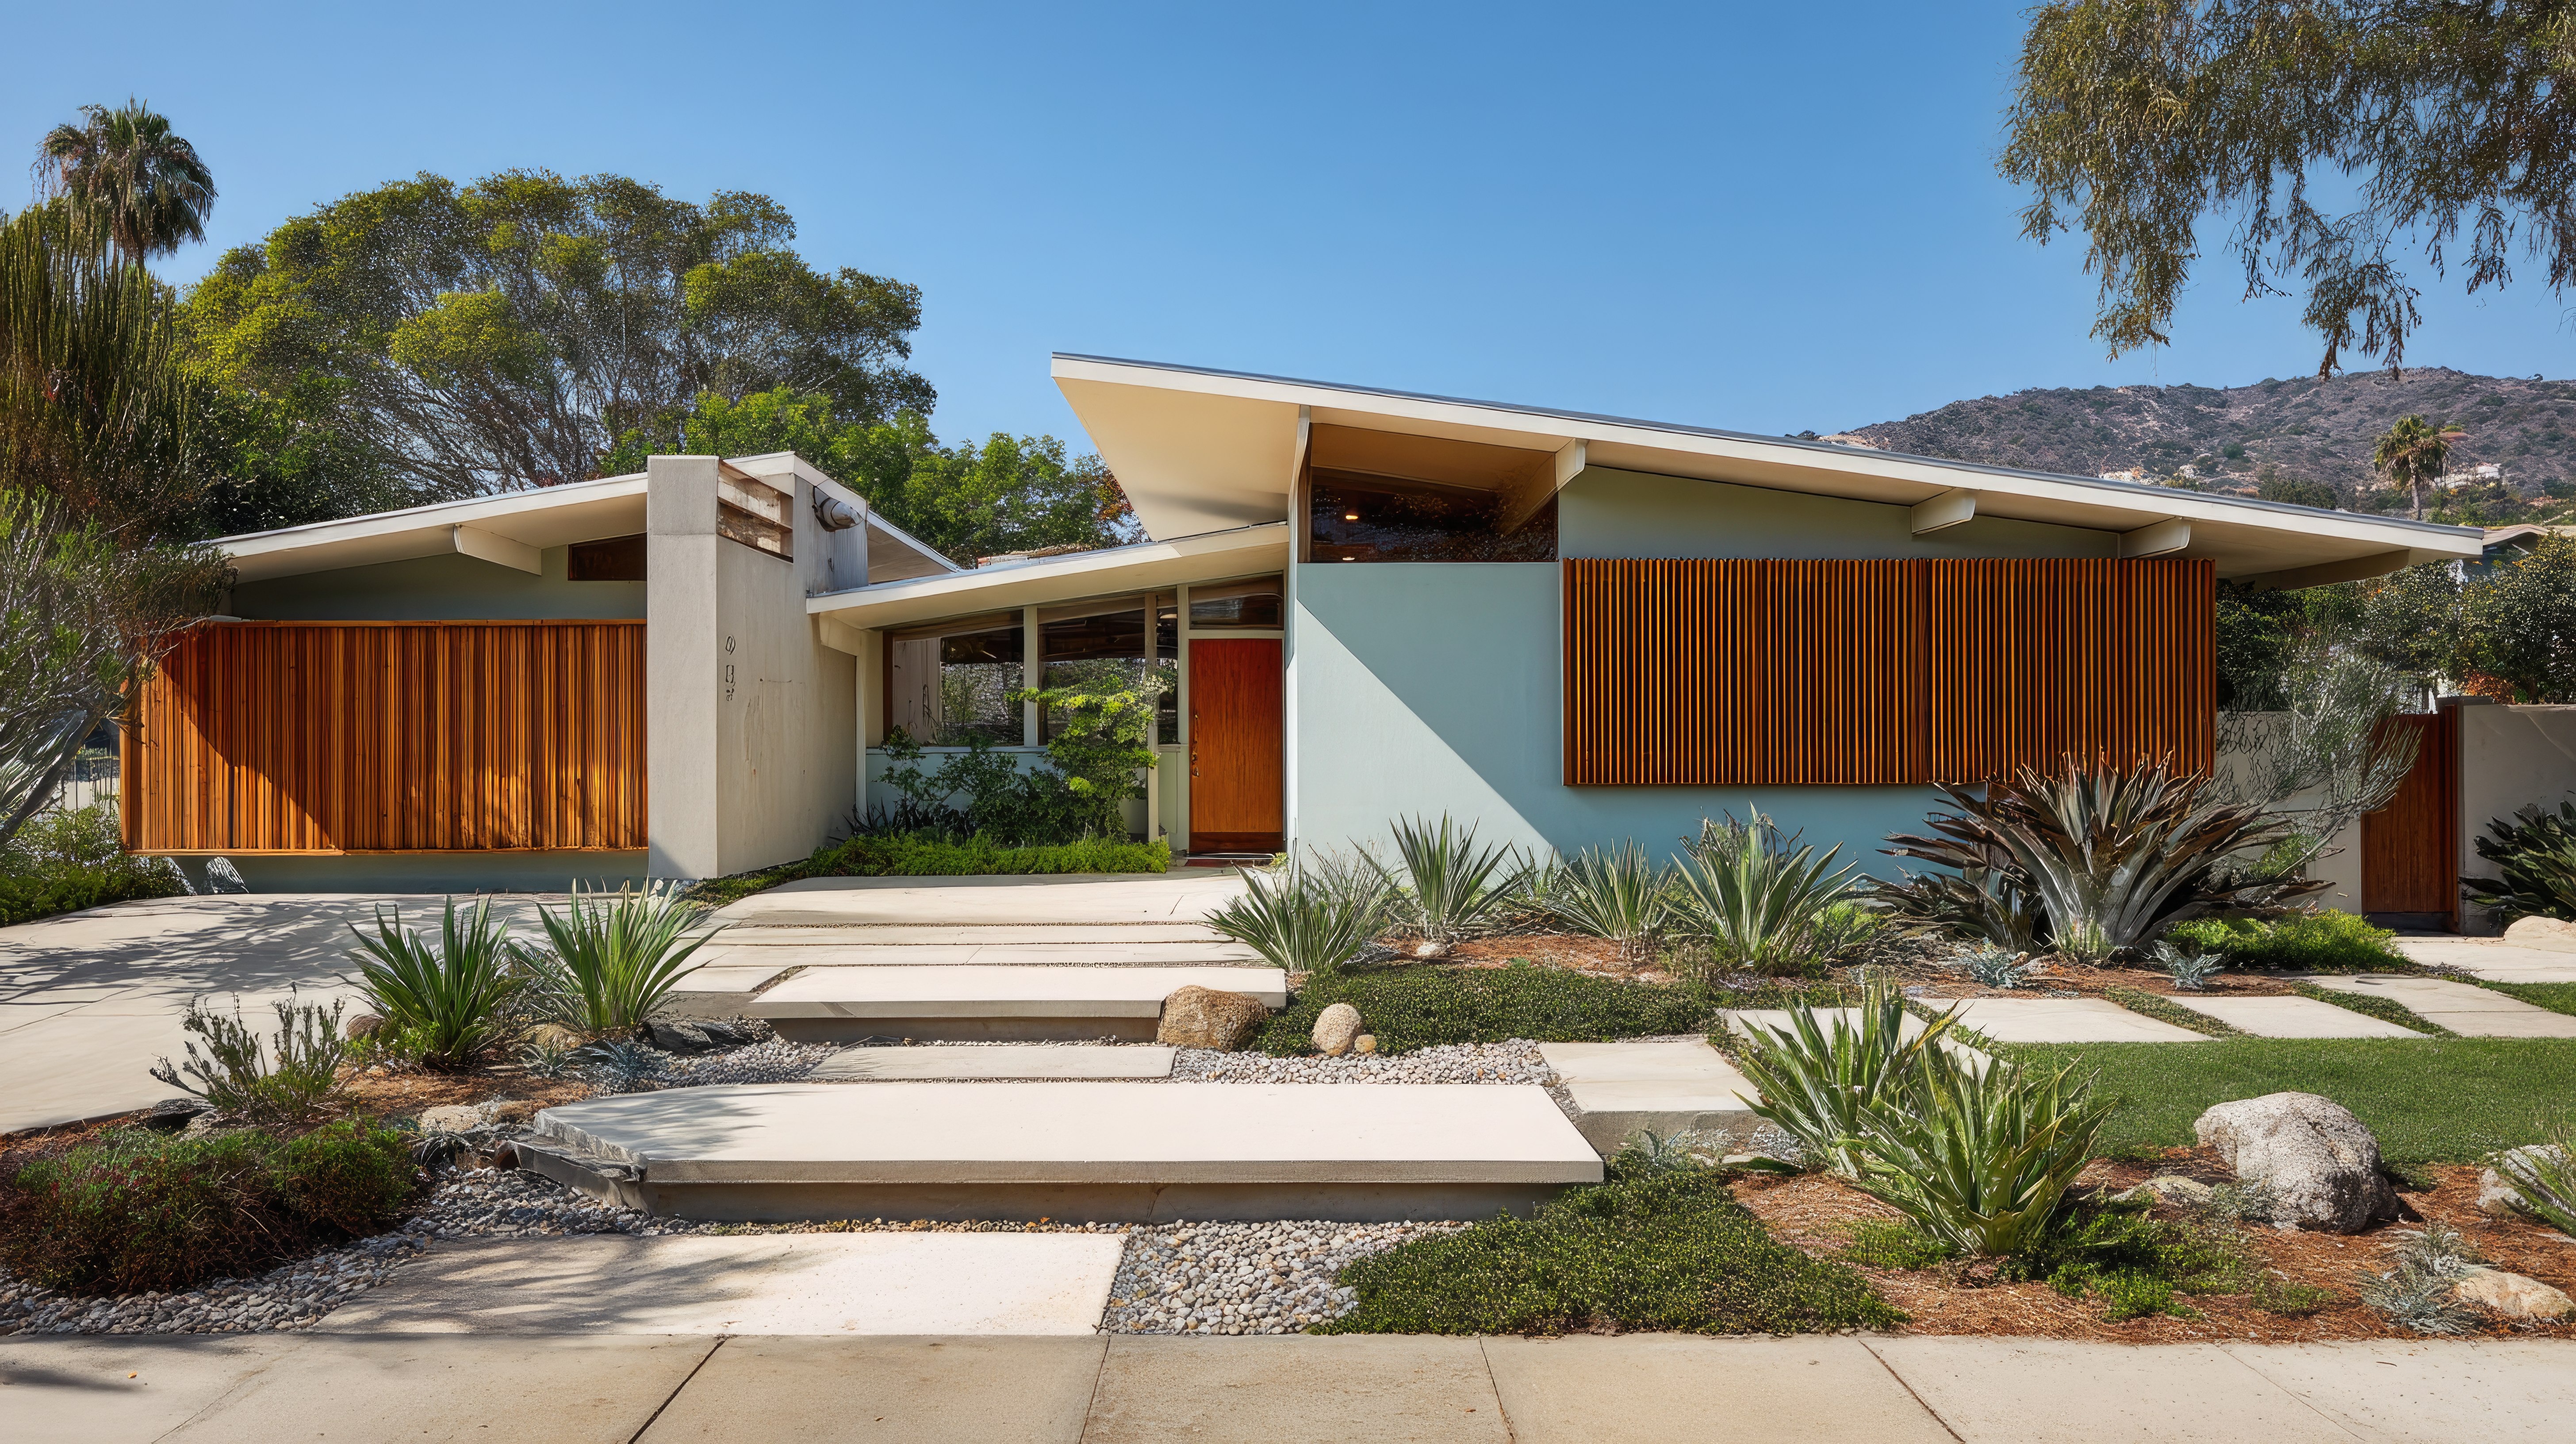
A real case study: a recently retired Pasadena couple, after his 30+ years as an aerospace contractor, not yet drawing pensions, Social Security or retirement distributions, found a single-level mid-century modern home near Annandale Canyon Park. We pre-approved them on their assets alone with a 60-month assets-as-income calculation, so they bought the $2.7M home with 50% down before selling the home where they raised their kids.
 Retirement
Retiring Teacher, Tahoe Cabin: Qualifying for a Second Home With Assets as Income
A real case study: a teacher from El Dorado Hills who had already given notice before retiring found the perfect cabin in South Lake Tahoe. His salary no longer counted, and he wasn't taking Social Security or retirement distributions yet. Our portfolio assets-as-income option used his $1,050,000 in retirement and investment accounts over 60 months to qualify him for a $695,000 second home with 30% down.
 Retirement
How to Qualify for a Mortgage in Retirement — Without Taking Taxable Distributions (Oregon & California, 2026)
You can qualify for a mortgage in retirement using your savings, investments, and retirement accounts — without starting a single taxable distribution. Here's how Oregon and California lenders actually convert assets, Social Security, and pensions into qualifying income, why the widely repeated numbers (the 70% "discount" and the 25% Social Security gross-up) are wrong, and why the timing of your application relative to your retirement date matters more than almost anything else.
Explore Further
Related tools & reading
All calculator results are estimates for informational purposes only and do not constitute a loan commitment or guarantee of any specific rate or terms. Actual loan terms will depend on creditworthiness, property type, and market conditions. Lumen Mortgage Corporation · NMLS #1498678 · Licensed in Oregon & California · 920 SW 6th Ave, Suite 1200, Portland, OR 97204.