IRA Loan Calculator
Estimate qualifying income from your IRA balances — traditional, SEP, Roth, and inherited IRAs divided by 36 (100% if you're 59½ or older, 90% if not) — plus Social Security, pension, W-2, or other income.

Get Started in 3 Steps
How to Use the IRA Loan Calculator
Enter Your IRA Balances
Add your traditional, SEP, Roth, and inherited IRA balances and choose whether the owner is 59½ or older (100%) or younger (90%).
Add Other Income
Include Social Security, pension, W-2, 1099, or similar monthly income. It's added to your IRA income.
Review Your Qualifying Income
See your IRA income, other income, and total monthly qualifying income, then send your results for review.
IRA Loan Calculator
Eligible IRA balance ÷ 36, plus your other income
Your IRA balances
Only IRAs count toward this program. 401(k)s, 403(b)s, cash, and brokerage accounts aren't included — model those in the Assets as Income Calculator.
Other income (optional)
IRA income
Eligible IRA balance ÷ 36
$6,944/mo
Total qualifying income
IRA income plus other income
$6,944/mo
$250,000 IRA × 100% ÷ 36 = $6,944
Want us to check these numbers?
Send your results and we'll review your IRA statements and other income against the program. Your numbers carry over automatically.
Or call 503-966-9255
This is an estimate, not a commitment to lend or an approval. IRA qualifying income is the total eligible IRA balance (traditional, SEP, Roth, and inherited IRAs) at 100% if the owner is 59½ or older or 90% if younger, divided by 36. 401(k)s and other employer plans, cash, and brokerage accounts are not part of this program. Other income must be documented and is subject to underwriting. Qualifying also depends on debt-to-income, credit, loan-to-value, and other program guidelines. Final qualifying income is determined by the underwriter after a full review. Lumen Mortgage · NMLS #1498678 · Licensed in Oregon & California. Equal Housing Lender.
How is IRA income calculated for a mortgage?
Our IRA loan program adds up your traditional, SEP, Roth, and inherited IRA balances, uses 100% of the total if the owner is 59½ or older or 90% if younger, and divides by 36 to produce monthly qualifying income. No distributions are required. Other documented income — Social Security, pension, W-2, or 1099 — is added on top. 401(k)s, cash, and brokerage accounts aren't part of this program.
Best for: Retirees, early retirees, and borrowers just over the DTI limit whose savings sit mostly in IRAs
How It Works
Understanding the IRA Loan Calculator
Many borrowers have meaningful IRA savings but little monthly income on paper — early retirees who haven't started Social Security, self-employed borrowers whose write-offs push DTI too high, or surviving spouses with an inherited IRA. Our IRA loan program qualifies you on the balance itself, with no distributions required.
The math is simple. Add your eligible IRA balances, count 100% if the owner is 59½ or older or 90% if younger, and divide by 36. For example, a $250,000 IRA at 100% is $250,000 ÷ 36 = $6,944 a month; at 90% it's $225,000 ÷ 36 = $6,250 a month. Traditional, SEP, Roth, and inherited IRAs all count, and multiple IRAs can typically be combined. 401(k)s and other employer plans don't qualify for this program, and cash and brokerage accounts aren't added to it — if your assets include those, compare our assets-as-income calculator, which models the 60-month asset depletion program alongside Fannie Mae and Freddie Mac.
Enter your balances, set the 59½ toggle, and add any other monthly income. The calculator shows your IRA income, your other income, and your total monthly qualifying income. To see how that income supports a payment, pair it with our DTI calculator. Final qualifying income is always set by the underwriter after reviewing your statements.
Ready to apply?
Numbers look right? Explore our IRA Loans page for eligibility details, rates, and next steps.
About This Calculator
What the IRA Loan Calculator is For
Our IRA loan program qualifies you on the balance of your individual retirement accounts — no distributions required. This calculator models the program's rule: add up your traditional, SEP, Roth, and inherited IRA balances, count 100% if the owner is 59½ or older or 90% if younger, and divide by 36 to get monthly qualifying income. Then stack your other documented income, such as Social Security, pension, W-2, or 1099 earnings. Only IRAs count: 401(k)s, 403(b)s, cash, and brokerage accounts aren't part of this program — model those in our Assets as Income Calculator.
Common Use Cases
- Retirees and early retirees qualifying on IRA balances without taking distributions
- Borrowers just over the DTI limit adding IRA income to close the gap
- Surviving spouses qualifying on an inherited IRA
Ready to turn numbers into a loan?
Or call 503-966-9255Common Questions
IRA Loan Calculator — Frequently Asked Questions
Keep Exploring
Related Calculators
Assets as Income Calculator
Turn cash, investments, and retirement accounts into qualifying income
Debt-to-Income Calculator
Calculate your front-end housing ratio and back-end total DTI using gross income and all monthly obligations
Mortgage Calculator
Estimate your monthly principal & interest payment, compare 15- vs. 30-year terms, and see total interest paid over the life of the loan
Bank Statement Income Calculator
Estimate qualifying income for self-employed borrowers using 12 or 24 months of bank deposits
From the Blog
Further Reading
 First-Time Buyers
First-Time Home Buyer Guide for Nurses: 3% Down and No PMI on Loans up to $2M
Buying your first home as a nurse? Here's how a nurse home loan works, how much you need down, how offer letters, travel contracts and student loans are handled, and a step-by-step plan from pre-approval to closing.
 Home Buying
Should You Rent or Buy a Home in Oregon or California? The 2026 Break-Even Guide
Renting isn't throwing money away, and buying isn't automatically an investment. Here's what each really costs in Oregon and California, how rent caps, Prop 13, Measure 50 and the 2026 tax rules change the math, and two worked examples showing the year buying pulls ahead.
 Retirement
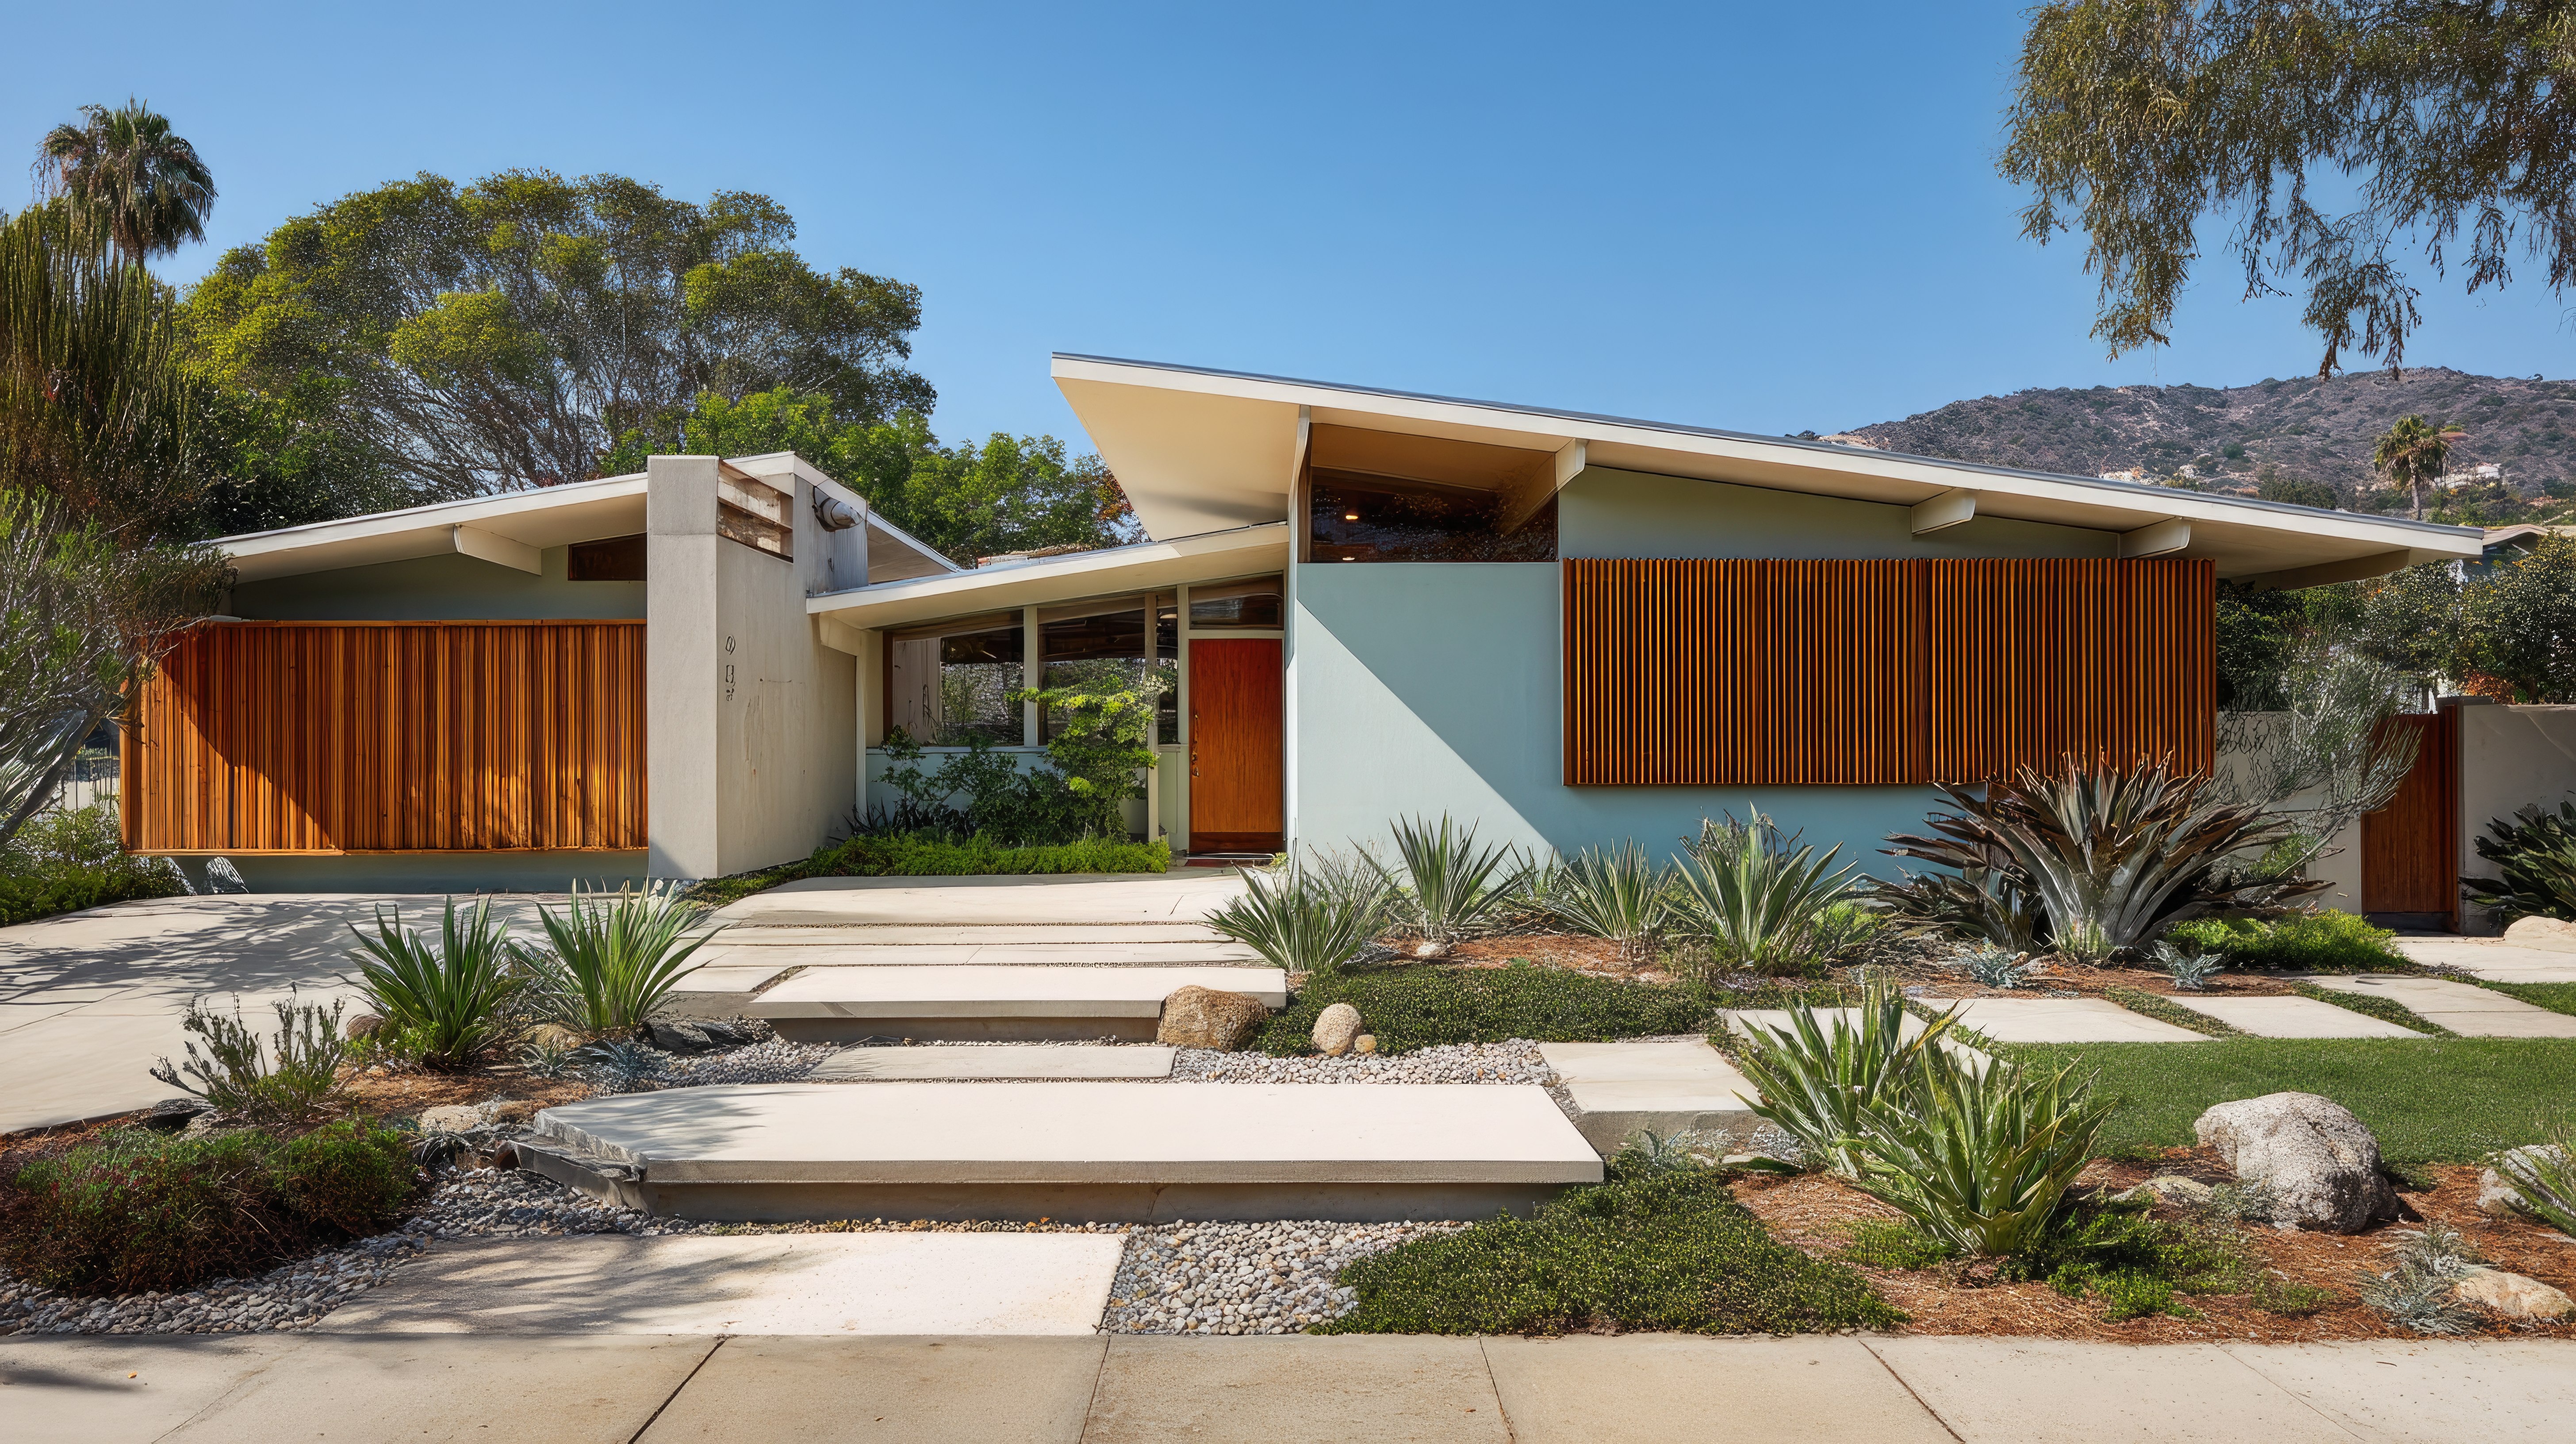
Pasadena Retirees Downsize: Buying Before Selling With Assets as Income
A real case study: a recently retired Pasadena couple, after his 30+ years as an aerospace contractor, not yet drawing pensions, Social Security or retirement distributions, found a single-level mid-century modern home near Annandale Canyon Park. We pre-approved them on their assets alone with a 60-month assets-as-income calculation, so they bought the $2.7M home with 50% down before selling the home where they raised their kids.
All calculator results are estimates for informational purposes only and do not constitute a loan commitment or guarantee of any specific rate or terms. Actual loan terms will depend on creditworthiness, property type, and market conditions. Lumen Mortgage Corporation · NMLS #1498678 · Licensed in Oregon & California · 920 SW 6th Ave, Suite 1200, Portland, OR 97204.