
Hood River · Columbia Gorge · NMLS #1498678
Mortgage lender for Hood River and the Columbia Gorge: orchards, vineyards, and second homes
Pear and apple orchards, Gorge vineyards, weekend homes, and view estates across Hood River and Wasco counties — agricultural, jumbo, second home, and DSCR financing, every cost itemized upfront, and an average clear-to-close of 17 days.
30
Residential Programs
Of 50+ total programs
17
Day Avg. Close
Clear-to-close timeline
$25M+
Agricultural Loans
Orchards, vineyards, ranches
$0
Surprise Fees
Itemized on day one
Lumen Mortgage Corporation (NMLS #1498678) is licensed in California and Oregon, financing homes, second homes, orchards, and vineyards in Hood River, Odell, Parkdale, Mosier, Cascade Locks, and The Dalles across the Columbia Gorge. We offer 50+ loan programs spanning residential, multifamily, agricultural and commercial, with an average clear-to-close of 17 days.
Who is a good mortgage lender in Hood River and the Columbia Gorge, Oregon?
Lumen Mortgage finances homes, second homes, orchards, and vineyards across Hood River and the Columbia Gorge, including Hood River, Odell, Parkdale, Mosier, Cascade Locks, and The Dalles. We offer 30 residential programs (50+ loan programs spanning residential, multifamily, agricultural and commercial), an average 17-day clear-to-close, and every cost itemized upfront. That includes agricultural loans for orchards and vineyards, jumbo and second home financing, DSCR loans for rentals, and asset-based qualifying for retirees.
Best for: Orchard and vineyard buyers, Portland second-home buyers, short-term rental investors, view-estate and acreage buyers, and local first-time buyers.
2026 Market Numbers
What are the loan limits in Hood River County?
Hood River County's 2026 limits are the $832,750 conforming baseline and a $762,450 FHA limit, the highest FHA limit in Oregon. Oregon has no high-balance conforming tier, so anything above $832,750 is jumbo. The typical home is about $705,000 in Hood River, $703,000 in Parkdale, $565,000 in Mosier, and $394,000 in The Dalles, so many view homes, acreage, and orchards need jumbo or agricultural financing, while FHA reaches further here than anywhere else in the state.
Hood River typical home value
~$705K
Zillow, Sep 2026 (up 2.7%)
Parkdale typical home value
~$703K
Zillow, Sep 2026 (up 3.1%)
Hood River County typical home value
~$682K
Zillow, Sep 2026 (up 2.6%)
Mosier typical home value
~$565K
Zillow, Sep 2026 (down 2.4%)
The Dalles typical home value
~$394K
Zillow, Sep 2026 (up 2.3%)
Conforming · FHA limit
$832,750 · $762,450
1 unit, Hood River County, 2026
Conforming: 2 · 3 · 4 units
$1,066,250 · $1,288,800 · $1,601,750
Hood River County, 2026
FHA: 2 · 3 · 4 units
$976,100 · $1,179,850 · $1,466,250
Hood River County, 2026
Wasco County FHA limit
$541,287
1 unit, The Dalles and Mosier, 2026
Home values are approximate, based on public market reports. Loan limits are 2026 FHFA and HUD figures. Sources: FHFA, HUD FHA limits, Zillow (Hood River), Zillow (Parkdale), Zillow (Hood River County), Zillow (Mosier), Zillow (The Dalles).
Built for the Columbia Gorge
Which loan fits a Hood River purchase?
Buyers here are often buying an orchard or vines, adding a weekend home from Portland, or buying their first home in the valley. Here's how we match programs to the way people actually buy here.
Orchards and farms
The Hood River Valley is one of the country's top pear-growing regions, with apple and cherry orchards from Odell to Parkdale. A home with a few acres of fruit trees may fit a residential or hobby farm loan; a working orchard fits an agricultural loan.
Vineyards and wineries
The Columbia Gorge AVA runs from the Hood River Valley east through Mosier toward The Dalles. We finance producing vineyards, wineries, and tasting-room properties, as well as homes with a few rows of vines.
Second homes and weekend escapes
Portland buyers come for windsurfing, kiteboarding, skiing on Mt. Hood, and mountain biking. Second homes start at 10% down, and jumbo goes above the $832,750 limit with 10% down for most buyers and no mortgage insurance.
View estates and acreage
Homes with Mt. Hood or Columbia River views and acreage in the upper valley often run above the $832,750 limit. Jumbo offers a 40-year fixed with 10 years interest-only and no autopay or banking-relationship requirement. Asset-based and bank statement loans qualify retirees and business owners.
First homes and local families
Hood River County's FHA limit is $762,450, the highest in Oregon, so FHA reaches further here than anywhere else in the state. The Dalles and Mosier are in Wasco County, where FHA goes up to $541,287. VA offers 0% down, and USDA 0% down in eligible rural areas.
Investors, ADUs, and custom homes
DSCR loans qualify rentals on the property's rent, with a 620+ credit score. Construction loans fund custom homes, ADUs, barns, and winery or packing buildings on your land.
Residential Programs
Home loans available in Hood River and the Gorge
Hood River buyers can choose from agricultural, jumbo, second home, DSCR, hobby farm, asset depletion, bank statement, vacation home, bridge, construction, physician, conventional, FHA, VA, USDA, first-time buyer, and DSCR loans. The right one depends mostly on the price of the home and how you earn your income.
| Purchase price | Usual best fit | Typical areas |
|---|---|---|
| Up to $541,287 | FHA 3.5% down anywhere in the Gorge, conventional from 3% down, VA 0% down; USDA 0% down in eligible rural areas | The Dalles, Cascade Locks, Dufur, Mosier condos and smaller homes |
| $541,287 – $762,450 | FHA 3.5% down in Hood River County; conventional; VA 0% down | Hood River, Odell, Parkdale, Mosier |
| $762,450 – $832,750 | Conventional up to the $832,750 limit; VA 0% down; physician loans | The Heights, Westside, Pine Grove |
| Above $832,750 | Jumbo — 10% down for most buyers and 0% down for VA and physician loans, no mortgage insurance, 40-year fixed with 10 years interest-only available | View estates, upper-valley acreage, riverfront homes |
| Orchards, vineyards, and ranches | Agricultural, hobby farm, or equestrian loans depending on the land and its income | Odell, Parkdale, Dee, Mosier, Columbia Gorge AVA |
Price ranges assume a single-family primary residence and are guides, not approvals. Your best program depends on credit, down payment, income, and the property.
Agricultural
Orchards, vineyards, and ranches. $500K–$25M+.
Jumbo
10% down for most buyers; 0% for VA and physicians. No MI.
Vacation Home
Second homes from 10% down.
DSCR
Qualify on rental income. 620+ credit.
Hobby Farm
Acreage with wells, septic, and outbuildings.
Equestrian
Horse property, barns, and arenas.
Asset Depletion
Qualify on savings and investments.
Bank Statement
Qualify on 12–24 months of deposits.
Bridge
Buy your next home before you sell.
Construction
Custom homes, ADUs, and barns.
Physician
For doctors and medical professionals.
Conventional
Up to the $832,750 limit.
FHA
3.5% down. Up to $762,450 in Hood River County.
VA
0% down, no monthly mortgage insurance.
USDA
0% down in eligible rural areas.
First-Time Buyer
Low down payment options.
Local Knowledge
What's different about financing a Hood River property?
Exclusive Farm Use zoning
Much of the valley's farmland is zoned EFU, which limits new homes and non-farm uses. Confirm what the zoning allows before you plan a build, guest house, or tasting room.
Water rights and irrigation districts
Irrigated vineyards, orchards, and pasture usually depend on water rights or irrigation district service. Ask for the water records before you write an offer.
Residential or agricultural?
A home with some vines or a barn is residential. A producing orchard, vineyard, winery, or ranch is agricultural. The choice changes down payment, rate, and term, so we decide it before you write an offer.
Luxury and estate appraisals
Estates with acreage, barns, or winery buildings have few direct comparables. We order early and use appraisers who know the Gorge.
Short-term rental rules
Hood River, Hood River County, Wasco County, and The Dalles each set their own short-term rental rules. Confirm the property can be used as a rental before you count on that income.
Insurance first in wildfire country
Some hillside and rural homes can be harder to insure. Your premium is part of your payment and debt-to-income ratio, so we start quotes during pre-approval.
Communities Served
Where in the Columbia Gorge do you lend?
Everywhere from Hood River, Odell, and Parkdale to Mosier, Cascade Locks, and The Dalles — and the rest of Oregon.
More Oregon: Portland · Oregon Coast · Bend · Willamette Valley · Rogue Valley. Looking for land or horses? See our equestrian property loans.
Preferred Agents
Looking for a great real estate agent in Hood River or the Gorge?
Are you looking for a knowledgeable agent who can help you find the best options for your family, schools, work, recreation, and investments in the Gorge? We work with the best agents in the region, and we'd be happy to make an introduction.
- Schools and neighborhoods
- Commutes and remote-work setups
- Luxury and estate properties
- Vineyard, winery, and horse property
- Second homes and Portland relocations
- Investment opportunities
Client Reviews
What Oregon borrowers say
5.0 stars across 62 reviews: 40 Google reviews · 15 Zillow reviews · 7 Yelp reviews
"They made everything so easy, simple and quick!"
"David was great to work with. He answered all our questions and explained things in terms we could understand. We worked with him when we first bought our home and again when we refinanced. … I highly recommend this company to anyone looking to buy a new home or refinance."
Sara G.
Bend homebuyer & refinance client · Google review
"From start to finish, he made the entire process feel effortless and filled us with confidence."
"Working with David from Lumen Mortgage has been an absolute joy. David helped us refinance our previous home and guided us through purchasing our new one with such grace and expertise. … His genuine attentiveness made all the difference. We felt like we were in the best hands, and we are so grateful for his support and guidance. If you're looking for someone who truly goes above and beyond, he is your person. We can't recommend him enough!"
Saam & Sally T.
Portland refinance & purchase clients · Google review
"David was kind and super helpful in answering my questions about a new ADU project. Would highly recommend him!"
Sheena D.
Washington County homeowner, ADU project · Google review
FAQ
Common questions from Hood River buyers
What are the 2026 loan limits in Hood River County?
Do I need a jumbo loan to buy in Hood River?
Do you finance orchards in the Hood River Valley?
Do you finance vineyards and wineries in the Columbia Gorge?
Is there a limit on how many acres I can finance in the Columbia Gorge?
How do farm zoning, the Scenic Area, and water rights affect a Hood River property?
Can I buy a second home in Hood River?
Can I finance a Hood River Airbnb or short-term rental?
Can I get a mortgage on a home in a high wildfire-risk area?
Is FHA a good option in Hood River County?
Can I buy my next Hood River home before I sell?
How fast can you close a mortgage in Hood River?
Free Tools
Run your numbers
The calculators our clients use most for this market. Part of our 20+ free tools.
Agricultural loan calculator
Payments and down payment on an orchard or vineyard.
Open calculatorJumbo loan calculator
View-home payments above the $832,750 limit.
Open calculatorFHA loan calculator
Payments up to Oregon's highest FHA limit, $762,450.
Open calculatorDSCR calculator
See if a rental's income covers the payment.
Open calculatorFurther Reading
Guides for Hood River buyers

Agricultural Lending in Oregon and California: Water Rights, Land Use Laws, SGMA, and the Underwriting Complexities That Make These States Different
16 min read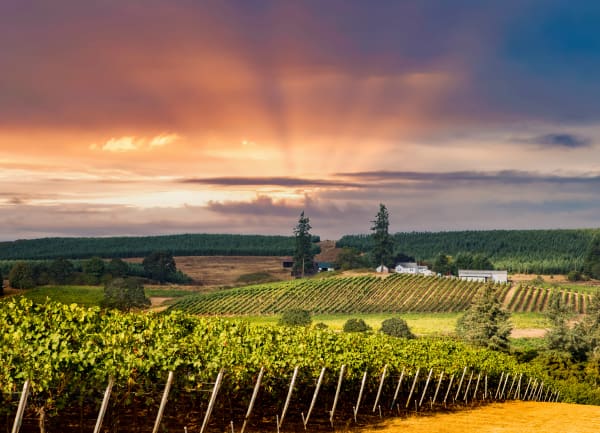
Financing Vineyard Properties in Oregon and California: How Use, Income, and Region Shape Your Loan Options
13 min read
Conventional vs. DSCR vs. DSCR Interest-Only: How a Brookings Oregon STR Borrower Picked the Right Investment-Property Loan
14 min readBuying in Hood River or the Gorge? Let's run your numbers.
No pressure, no sales pitch. Tell us about the home and we'll show you your options, costs, and timeline upfront. Or call us: 503-966-9255.
Lumen Mortgage Corporation · NMLS #1498678 · Equal Housing Lender · Licensed in Oregon and California. This is not a commitment to lend. All loan approvals subject to underwriting guidelines. Rate and program availability subject to change without notice.