Nurse Home Loan Calculator
Model our nurse home loan — 3% down with no mortgage insurance up to $2M and 89.99% financing up to $3M — side by side against a conventional loan with PMI. See your monthly savings, try a 2-1 or 1-0 buydown, and estimate reserves if you're qualifying on an offer letter.
Get Started in 3 Steps
How to Use the Nurse Home Loan Calculator
Enter Your Price & Profile
Set your purchase price, down payment (3% or more), credit score band, and loan term. The calculator shows your financing tier: 97% up to $2M or 89.99% up to $3M.
Compare Nurse vs. Conventional
See your nurse loan payment with no mortgage insurance next to a conventional loan with estimated PMI, using the same rate in both columns, plus your monthly and yearly savings.
Model Buydowns & Reserves
Try a 2-1 or 1-0 buydown on a 30-year fixed, and if you're qualifying on an offer letter, choose your start date to estimate the reserves you'll need.
Nurse Home Loan Calculator
3% Down to $2M · 89.99% to $3M · No PMI · vs. Conventional
Default rate for illustration, as of July 2026. Edit to match your quote.
Loan Amount
$533,500
LTV
97.0%
Term
30-yr fixed
Nurse Home Loan
RN, NP, CRNA, CNS · 1-unit primary residence modeled · 700+ credit
Monthly P&I
$3,729.94
Conventional with PMI
Monthly P&I
$3,729.94
Your nurse loan savings
$467/month
vs. a conventional loan with PMI at 3.0% down
Per year
$5,602
PMI avoided
$466.81/mo
Same rate assumed in both columns. The difference shown is mortgage insurance.
Estimates for illustration only, based on nurse home loan guidelines as of 2026: eligible RNs, NPs, CRNAs and clinical nurse specialists; 1-unit primary residence; purchase or rate/term refinance; Oregon & California. 97% financing to $2M and 89.99% to $3M with a 700 score for every borrower; $100,000 minimum loan; 50% maximum DTI. Reserves: 2 months PITI above $2M, plus one month for each month between closing and an offer-letter start date (up to 180 days). 2-1 and 1-0 temporary buydowns are available on 30-year fixed purchases. Second homes, 2–4 units and 5/6, 7/6 and 10/6 SOFR ARMs are available but not modeled here. Down payment excludes closing costs and prepaids. No mortgage insurance. PMI figures in the conventional column are market estimates, not quotes. Subject to credit approval and program guidelines. NMLS #1498678.
How much can a nurse save with a 3%-down, no-PMI home loan?
Our nurse home loan finances up to 97% of the price (3% down) on loans up to $2,000,000 and 89.99% up to $3,000,000, with no mortgage insurance. On a $550,000 home with 3% down, a conventional loan would carry roughly $467 a month in estimated PMI, about $5,600 a year, that the nurse loan avoids. This calculator shows that difference at any price and down payment.
Best for: Registered nurses, nurse practitioners, CRNAs, and clinical nurse specialists buying in Oregon or California
How It Works
Understanding the Nurse Home Loan Calculator
The biggest difference between our nurse home loan and a low-down conventional loan is mortgage insurance. The nurse program has none, even at 3% down, while a conventional loan with less than 20% down adds PMI to every payment. This calculator puts the two side by side at the same rate, so the gap you see is the mortgage insurance you'd skip.
Worked example: you're buying a $550,000 home with 3% down ($16,500), for a $533,500 loan. A conventional loan at that down payment carries estimated PMI of about $467 a month. The nurse loan has no PMI, so you'd pay about $5,600 less a year for the same home and rate. Drag the down payment slider and the savings shrink as PMI drops, until both loans match at 20% down.
The program finances up to 97% on loans up to $2,000,000 and up to 89.99% up to $3,000,000, so above $2M you'll need just over 10% down. Every borrower needs a 700 credit score. Above the $832,750 conforming limit, a 3%-down conventional loan isn't available, so the calculator shows a note in that column instead of a comparison that couldn't happen. If you're qualifying on a signed offer letter, pick your start date to see the reserves you'll need: one month of payments for each month between closing and your first day, plus two months on loans above $2,000,000. On 30-year fixed purchases you can also model a 2-1 or 1-0 temporary buydown. Closing costs and prepaid items still apply, and final terms are confirmed in underwriting.
Ready to apply?
Numbers look right? Explore our Nurse Home Loans page for eligibility details, rates, and next steps.
About This Calculator
What the Nurse Home Loan Calculator is For
Our nurse home loan is built for registered nurses, nurse practitioners, CRNAs, and clinical nurse specialists who want to buy with a small down payment and no mortgage insurance. This calculator models the program's rules: 97% financing (3% down) on loans up to $2,000,000, 89.99% financing up to $3,000,000, a $100,000 minimum loan, and a 700 minimum credit score for every borrower. Set your purchase price, down payment, credit band, and term to see your monthly payment next to a conventional loan with estimated PMI, along with your monthly and yearly savings. On 30-year fixed purchases you can model a 2-1 or 1-0 temporary buydown, and if you're qualifying on a signed offer letter, choose your start date to estimate the reserves you'll need.
Common Use Cases
- Nurses comparing 3%-down, no-PMI financing to a conventional loan with mortgage insurance
- Estimating reserves when buying before an offer-letter start date
- Seeing what a 2-1 or 1-0 temporary buydown does to the first years' payments
Ready to turn numbers into a loan?
Or call 503-966-9255Common Questions
Nurse Home Loan Calculator — Frequently Asked Questions
Keep Exploring
Related Calculators
Physician Loan Calculator
Model our 100% Fixed and High-Balance & Flexible physician programs
Conventional & PMI Calculator
Calculate your conventional loan payment with FICO-score-based PMI rates, see exactly when PMI cancels under the Homeowners Protection Act, and find out how much you'd save by improving your credit score before applying.
Debt-to-Income Calculator
Calculate your front-end housing ratio and back-end total DTI using gross income and all monthly obligations
Mortgage Calculator
Estimate your monthly principal & interest payment, compare 15- vs. 30-year terms, and see total interest paid over the life of the loan
From the Blog
Further Reading
 First-Time Buyers
First-Time Home Buyer Guide for Nurses: 3% Down and No PMI on Loans up to $2M
Buying your first home as a nurse? Here's how a nurse home loan works, how much you need down, how offer letters, travel contracts and student loans are handled, and a step-by-step plan from pre-approval to closing.
 Home Buying
Should You Rent or Buy a Home in Oregon or California? The 2026 Break-Even Guide
Renting isn't throwing money away, and buying isn't automatically an investment. Here's what each really costs in Oregon and California, how rent caps, Prop 13, Measure 50 and the 2026 tax rules change the math, and two worked examples showing the year buying pulls ahead.
 Retirement
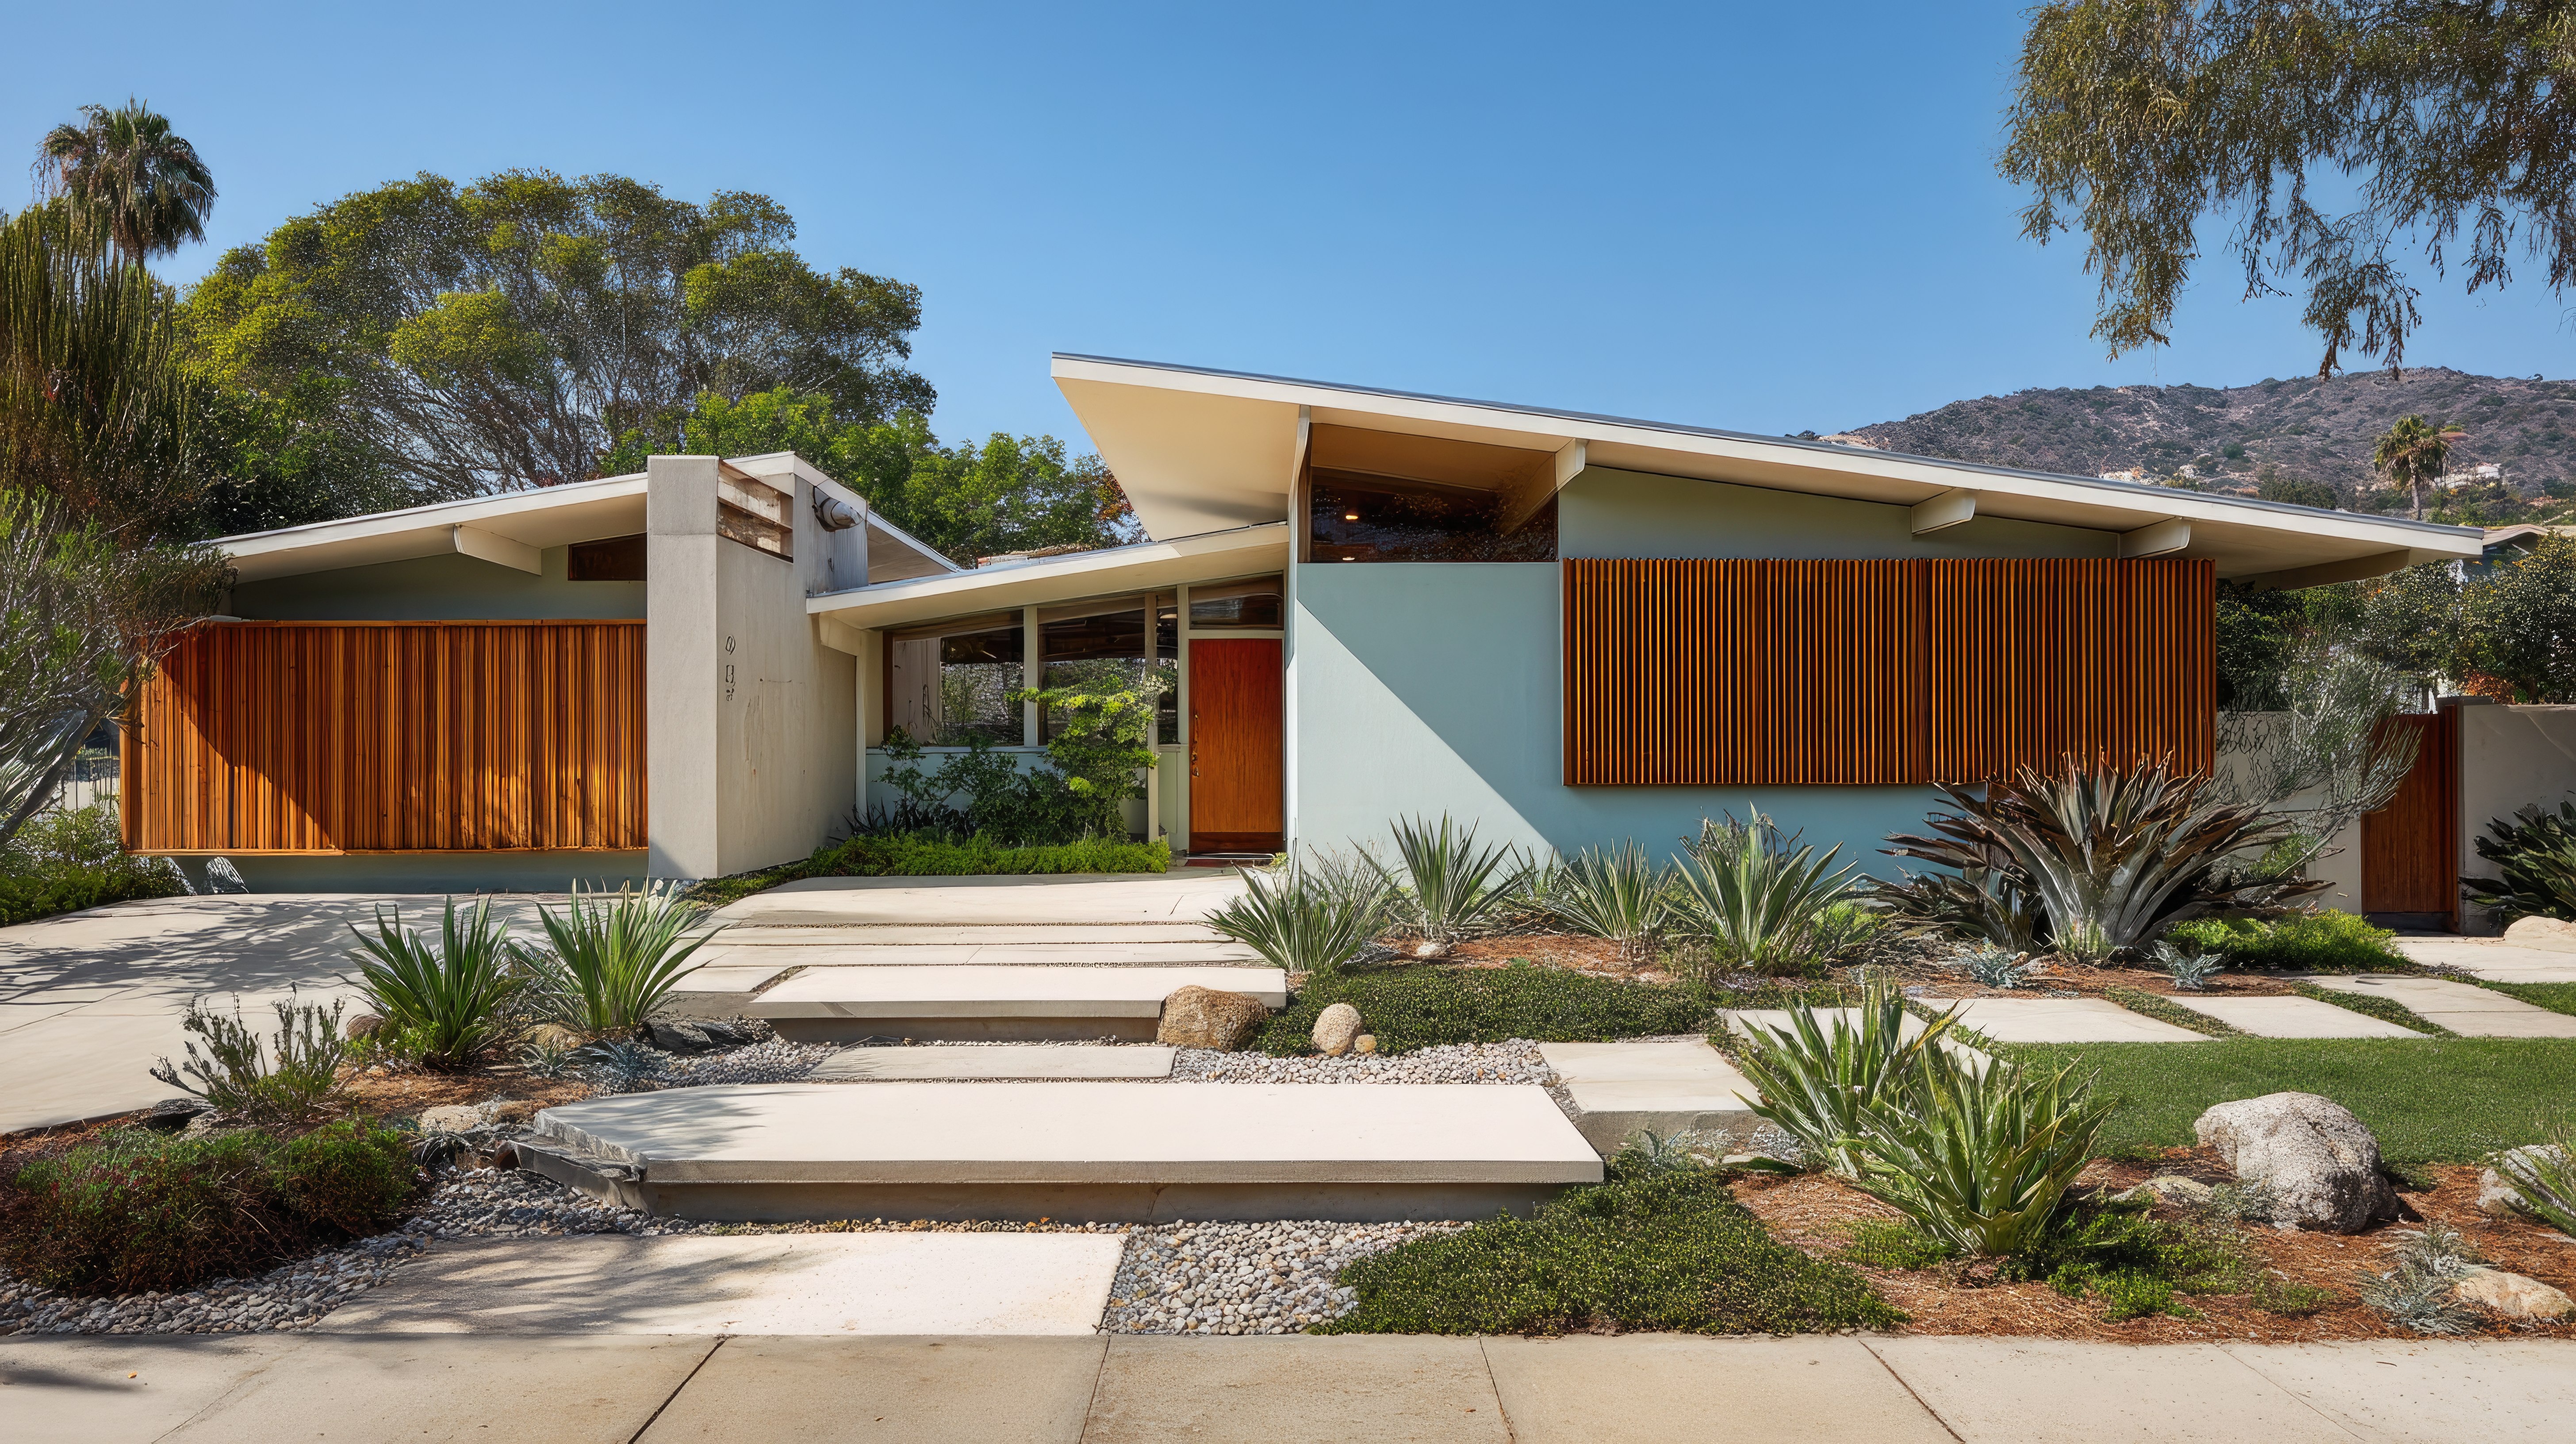
Pasadena Retirees Downsize: Buying Before Selling With Assets as Income
A real case study: a recently retired Pasadena couple, after his 30+ years as an aerospace contractor, not yet drawing pensions, Social Security or retirement distributions, found a single-level mid-century modern home near Annandale Canyon Park. We pre-approved them on their assets alone with a 60-month assets-as-income calculation, so they bought the $2.7M home with 50% down before selling the home where they raised their kids.
All calculator results are estimates for informational purposes only and do not constitute a loan commitment or guarantee of any specific rate or terms. Actual loan terms will depend on creditworthiness, property type, and market conditions. Lumen Mortgage Corporation · NMLS #1498678 · Licensed in Oregon & California · 920 SW 6th Ave, Suite 1200, Portland, OR 97204.