Rent vs. Buy Calculator
Compare renting with buying a home in Oregon or California. See first-year monthly costs, total costs, renter and buyer net worth year by year, and the year buying pulls ahead, using editable state assumptions.

Get Started in 3 Steps
How to Use the Rent vs. Buy Calculator
Enter Your ZIP and Rent
Load Oregon or California defaults from your ZIP, then enter your current rent, expected rent growth and renters insurance.
Set the Purchase and Loan
Enter the home price, down payment, rate and term, plus property tax rate, insurance, HOA, maintenance and closing and selling costs.
Compare Net Worth and Break-Even
Choose how long you'd stay and your expected appreciation and investment return, then compare monthly costs, total costs and net worth year by year.
Rent vs. Buy Calculator
Oregon & California: monthly cost, net worth and your break-even year
Location
Renting
Buying
Your plans & assumptions
Results for Oregon
If you move in year 7
Buying comes out ahead by
$51,244
Break-even
Year 4
Stay at least 4 years and buying leaves you with more net worth than renting, after selling costs.
First month: buying
$3,443
First month: renting
$3,020
Buying costs $423 more in month one. The calculator invests that difference for the renter. Principal paid builds equity; it isn't a cost.
Net worth from each choice
Buying: home value after selling costs, minus the loan, plus invested savings. Renting: invested cash.
- Buying
- Renting
Buying after 7 years
Paid along the way: $182,742 interest and $76,400 in other costs, net of any tax savings.
Renting after 7 years
Rent paid along the way: $277,688, including renters insurance.
Oregon rules in this estimate
- Measure 50: Oregon doesn't reassess on sale. Your bill starts near the seller's, and the assessed value can rise up to 3% a year. For the most accurate rate, divide the current tax bill by the price.
- Oregon follows the federal $750,000 limit on deductible mortgage interest.
- Oregon has no real estate transfer tax, except Washington County ($1 per $1,000).
Year-by-year comparison
| Year | Home value | Loan balance | Buying net worth | Renting net worth | Difference |
|---|---|---|---|---|---|
| 1 | $543,375 | $415,306 | $95,467 | $132,081 | Rent +$36,614 |
| 2 | $562,393 | $410,297 | $118,353 | $143,325 | Rent +$24,972 |
| 3 | $582,077 | $404,952 | $142,200 | $154,436 | Rent +$12,236 |
| 4 | $602,450 | $399,250 | $167,052 | $165,376 | Buy +$1,677 |
| 5 | $623,535 | $393,166 | $192,957 | $176,116 | Buy +$16,841 |
| 6 | $645,359 | $386,675 | $219,963 | $186,627 | Buy +$33,336 |
| 7 | $667,947 | $379,748 | $248,122 | $196,877 | Buy +$51,244 |
| 8 | $691,325 | $372,358 | $277,489 | $206,834 | Buy +$70,655 |
| 9 | $715,521 | $364,473 | $308,837 | $217,175 | Buy +$91,662 |
| 10 | $740,564 | $356,060 | $342,397 | $228,034 | Buy +$114,363 |
| 15 | $879,558 | $304,748 | $548,185 | $291,036 | Buy +$257,149 |
| 20 | $1,044,639 | $233,794 | $832,157 | $371,443 | Buy +$460,714 |
| 25 | $1,240,704 | $135,677 | $1,219,532 | $474,066 | Buy +$745,465 |
| 30 | $1,473,567 | $0 | $1,743,265 | $605,042 | Buy +$1,138,223 |
Estimates for education only. This is not a Loan Estimate, a commitment to lend, or an offer of credit. Starting prices, rents, rates and premiums are examples; enter your own. Home values, rents and investment returns are assumptions and can be lower or negative. Insurance, HOA dues and renters insurance are assumed to rise 3% a year. Investment returns are shown before taxes, and the home sale is assumed to fall within the capital gains exclusion. Property tax follows the state assessment cap described above. Tax savings, if included, count federal deductions above the 2026 standard deduction and assume your property tax fits under the SALT cap; state savings use your state bracket on deductible interest and ignore the state standard deduction. PMI pricing depends on credit and loan type. Lumen Mortgage does not provide tax, legal or investment advice. Lumen Mortgage · NMLS #1498678 · Licensed in Oregon & California. Equal Housing Lender.
Is it better to rent or buy a home in Oregon or California?
It depends mostly on how long you'll stay. Buying costs about 2–4% of the price to get in and often 6% or more to get out, and early payments are mostly interest. At this calculator's default assumptions, a $525,000 Oregon home beats $3,000 rent by year 4, and an $850,000 California home beats $4,000 rent by year 7. When rent is low relative to the price, break-even can slip past year 10, so run your own price, rent, rate and appreciation.
Best for: Oregon and California renters deciding whether to buy now or keep renting, and how long they'd need to stay for buying to pay off
How It Works
Understanding the Rent vs. Buy Calculator
The calculator runs both paths month by month for up to 30 years. The buyer pays the down payment and closing costs, then the mortgage, PMI if under 20% down, property tax, insurance, HOA and maintenance. The renter keeps the upfront cash invested and pays rent and renters insurance. Each month, whichever path costs less invests the difference at your expected return, so both paths spend the same money.
Buyer net worth is the home's value minus selling costs and the loan balance, plus any invested savings. Renter net worth is the investment portfolio. The break-even year is the first year the buyer comes out ahead, and the chart shows both lines through 30 years with your planned move year marked.
Property tax follows each state's rule. In California, Prop 13 resets the assessed value to your purchase price, then caps increases at 2% a year; buyers also get one or two supplemental tax bills after closing, which this tool doesn't model. In Oregon, Measure 50 caps assessed value growth at 3% a year and doesn't reset on sale, so the seller's current tax bill is a better guide than price times rate. Defaults are illustrative state averages, so replace them with quotes and tax bills for the home you're considering. For more on taxes and insurance, see our property tax, insurance and escrow guide.
Ready to apply?
Numbers look right? Explore our Conventional Loans page for eligibility details, rates, and next steps.
About This Calculator
What the Rent vs. Buy Calculator is For
Buying wins when the equity you build and the home's appreciation outrun what you'd earn by renting and investing the down payment, closing costs and any monthly savings. This calculator runs both paths month by month for up to 30 years: mortgage principal and interest, PMI until the loan reaches 78% of the original value, property tax, insurance, HOA and maintenance against rent and renters insurance, with whichever path costs less each month investing the difference. Buyer net worth is what you'd keep after selling costs; renter net worth is the invested portfolio. Enter a ZIP to load illustrative Oregon or California defaults, then edit every assumption. Property tax grows under each state's assessment cap (California Prop 13 at 2% a year, Oregon Measure 50 at 3%), and optional tax savings use the 2026 standard deduction and federal and state mortgage-interest limits.
Common Use Cases
- Renters deciding whether to buy now or keep renting and investing
- Comparing break-even years at different home prices, rates and holding periods
- Testing how Prop 13 or Measure 50 tax caps affect the cost of owning
Ready to turn numbers into a loan?
Or call 503-966-9255Common Questions
Rent vs. Buy Calculator — Frequently Asked Questions
Keep Exploring
Related Calculators
Mortgage Calculator
Estimate your monthly principal & interest payment, compare 15- vs. 30-year terms, and see total interest paid over the life of the loan
Conventional & PMI Calculator
Calculate your conventional loan payment with FICO-score-based PMI rates, see exactly when PMI cancels under the Homeowners Protection Act, and find out how much you'd save by improving your credit score before applying.
Debt-to-Income Calculator
Calculate your front-end housing ratio and back-end total DTI using gross income and all monthly obligations
Escrow & Impound Calculator
Estimate the property tax and homeowners insurance due at closing on a California or Oregon purchase or refinance. Compare full impounds, taxes only, insurance only, and no impounds, with CA supplemental tax estimates.
From the Blog
Further Reading
 Home Buying
Should You Rent or Buy a Home in Oregon or California? The 2026 Break-Even Guide
Renting isn't throwing money away, and buying isn't automatically an investment. Here's what each really costs in Oregon and California, how rent caps, Prop 13, Measure 50 and the 2026 tax rules change the math, and two worked examples showing the year buying pulls ahead.
 Retirement
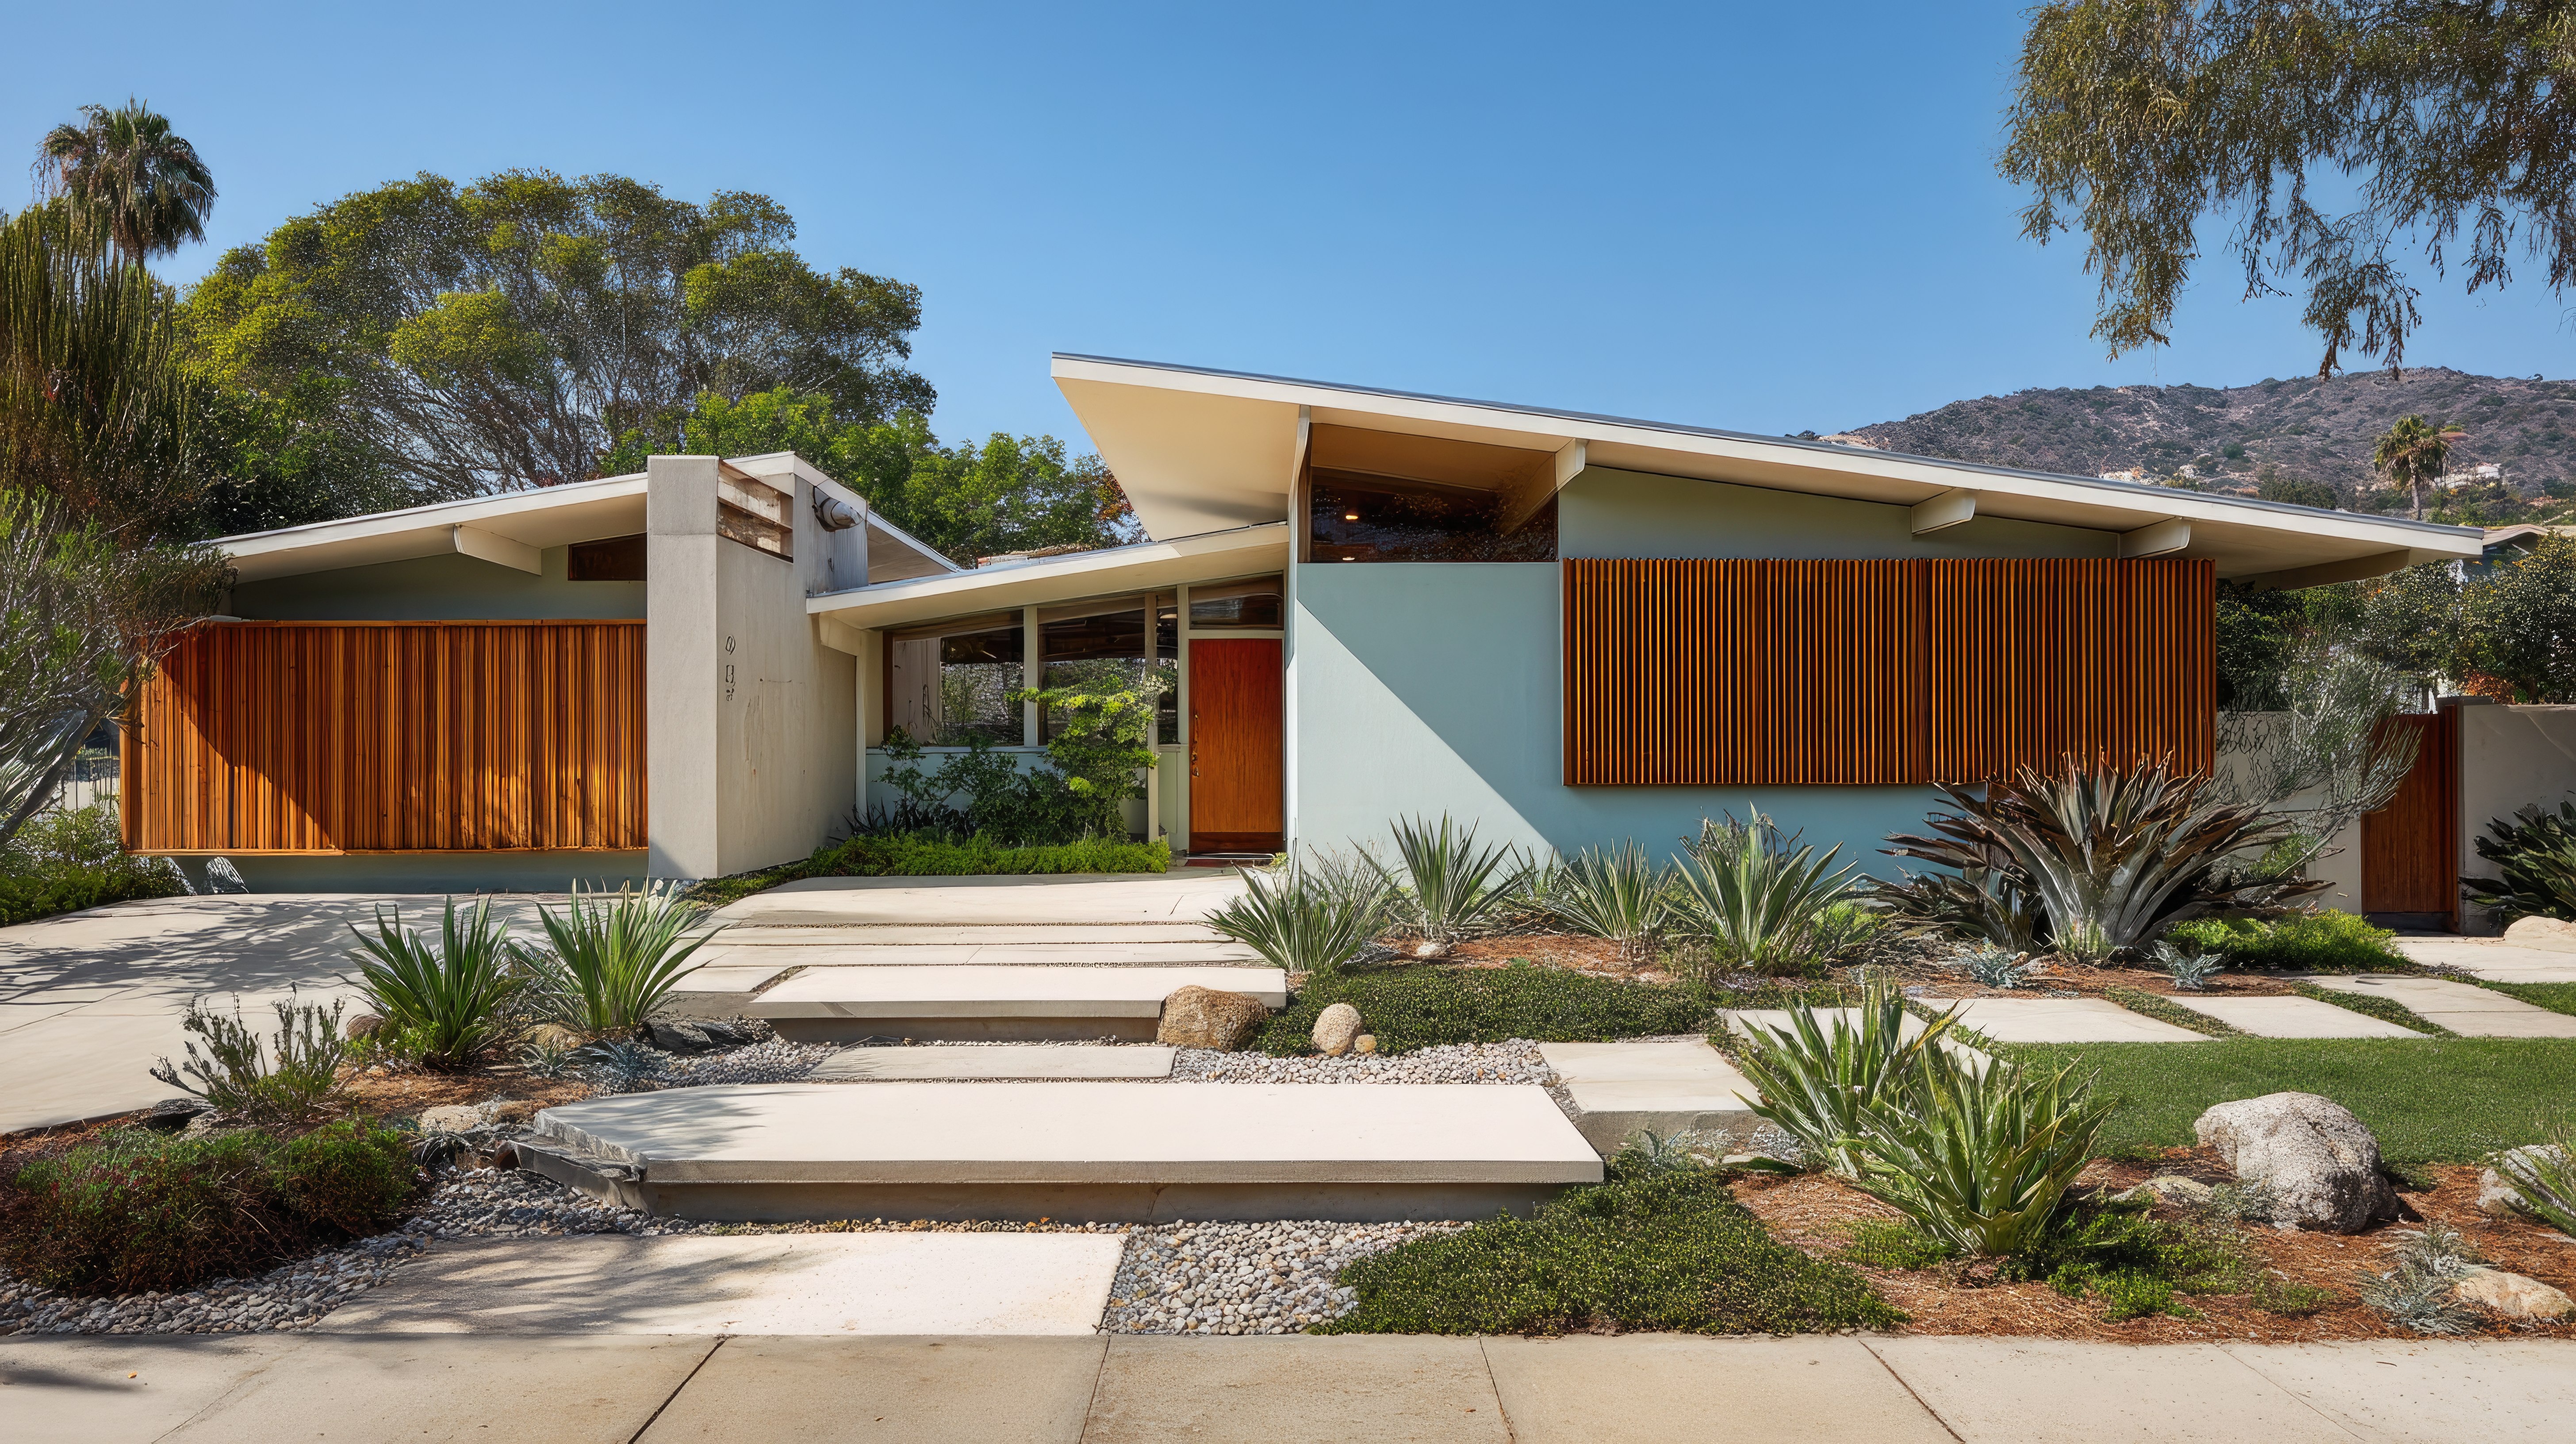
Pasadena Retirees Downsize: Buying Before Selling With Assets as Income
A real case study: a recently retired Pasadena couple, after his 30+ years as an aerospace contractor, not yet drawing pensions, Social Security or retirement distributions, found a single-level mid-century modern home near Annandale Canyon Park. We pre-approved them on their assets alone with a 60-month assets-as-income calculation, so they bought the $2.7M home with 50% down before selling the home where they raised their kids.
 Self-Employed
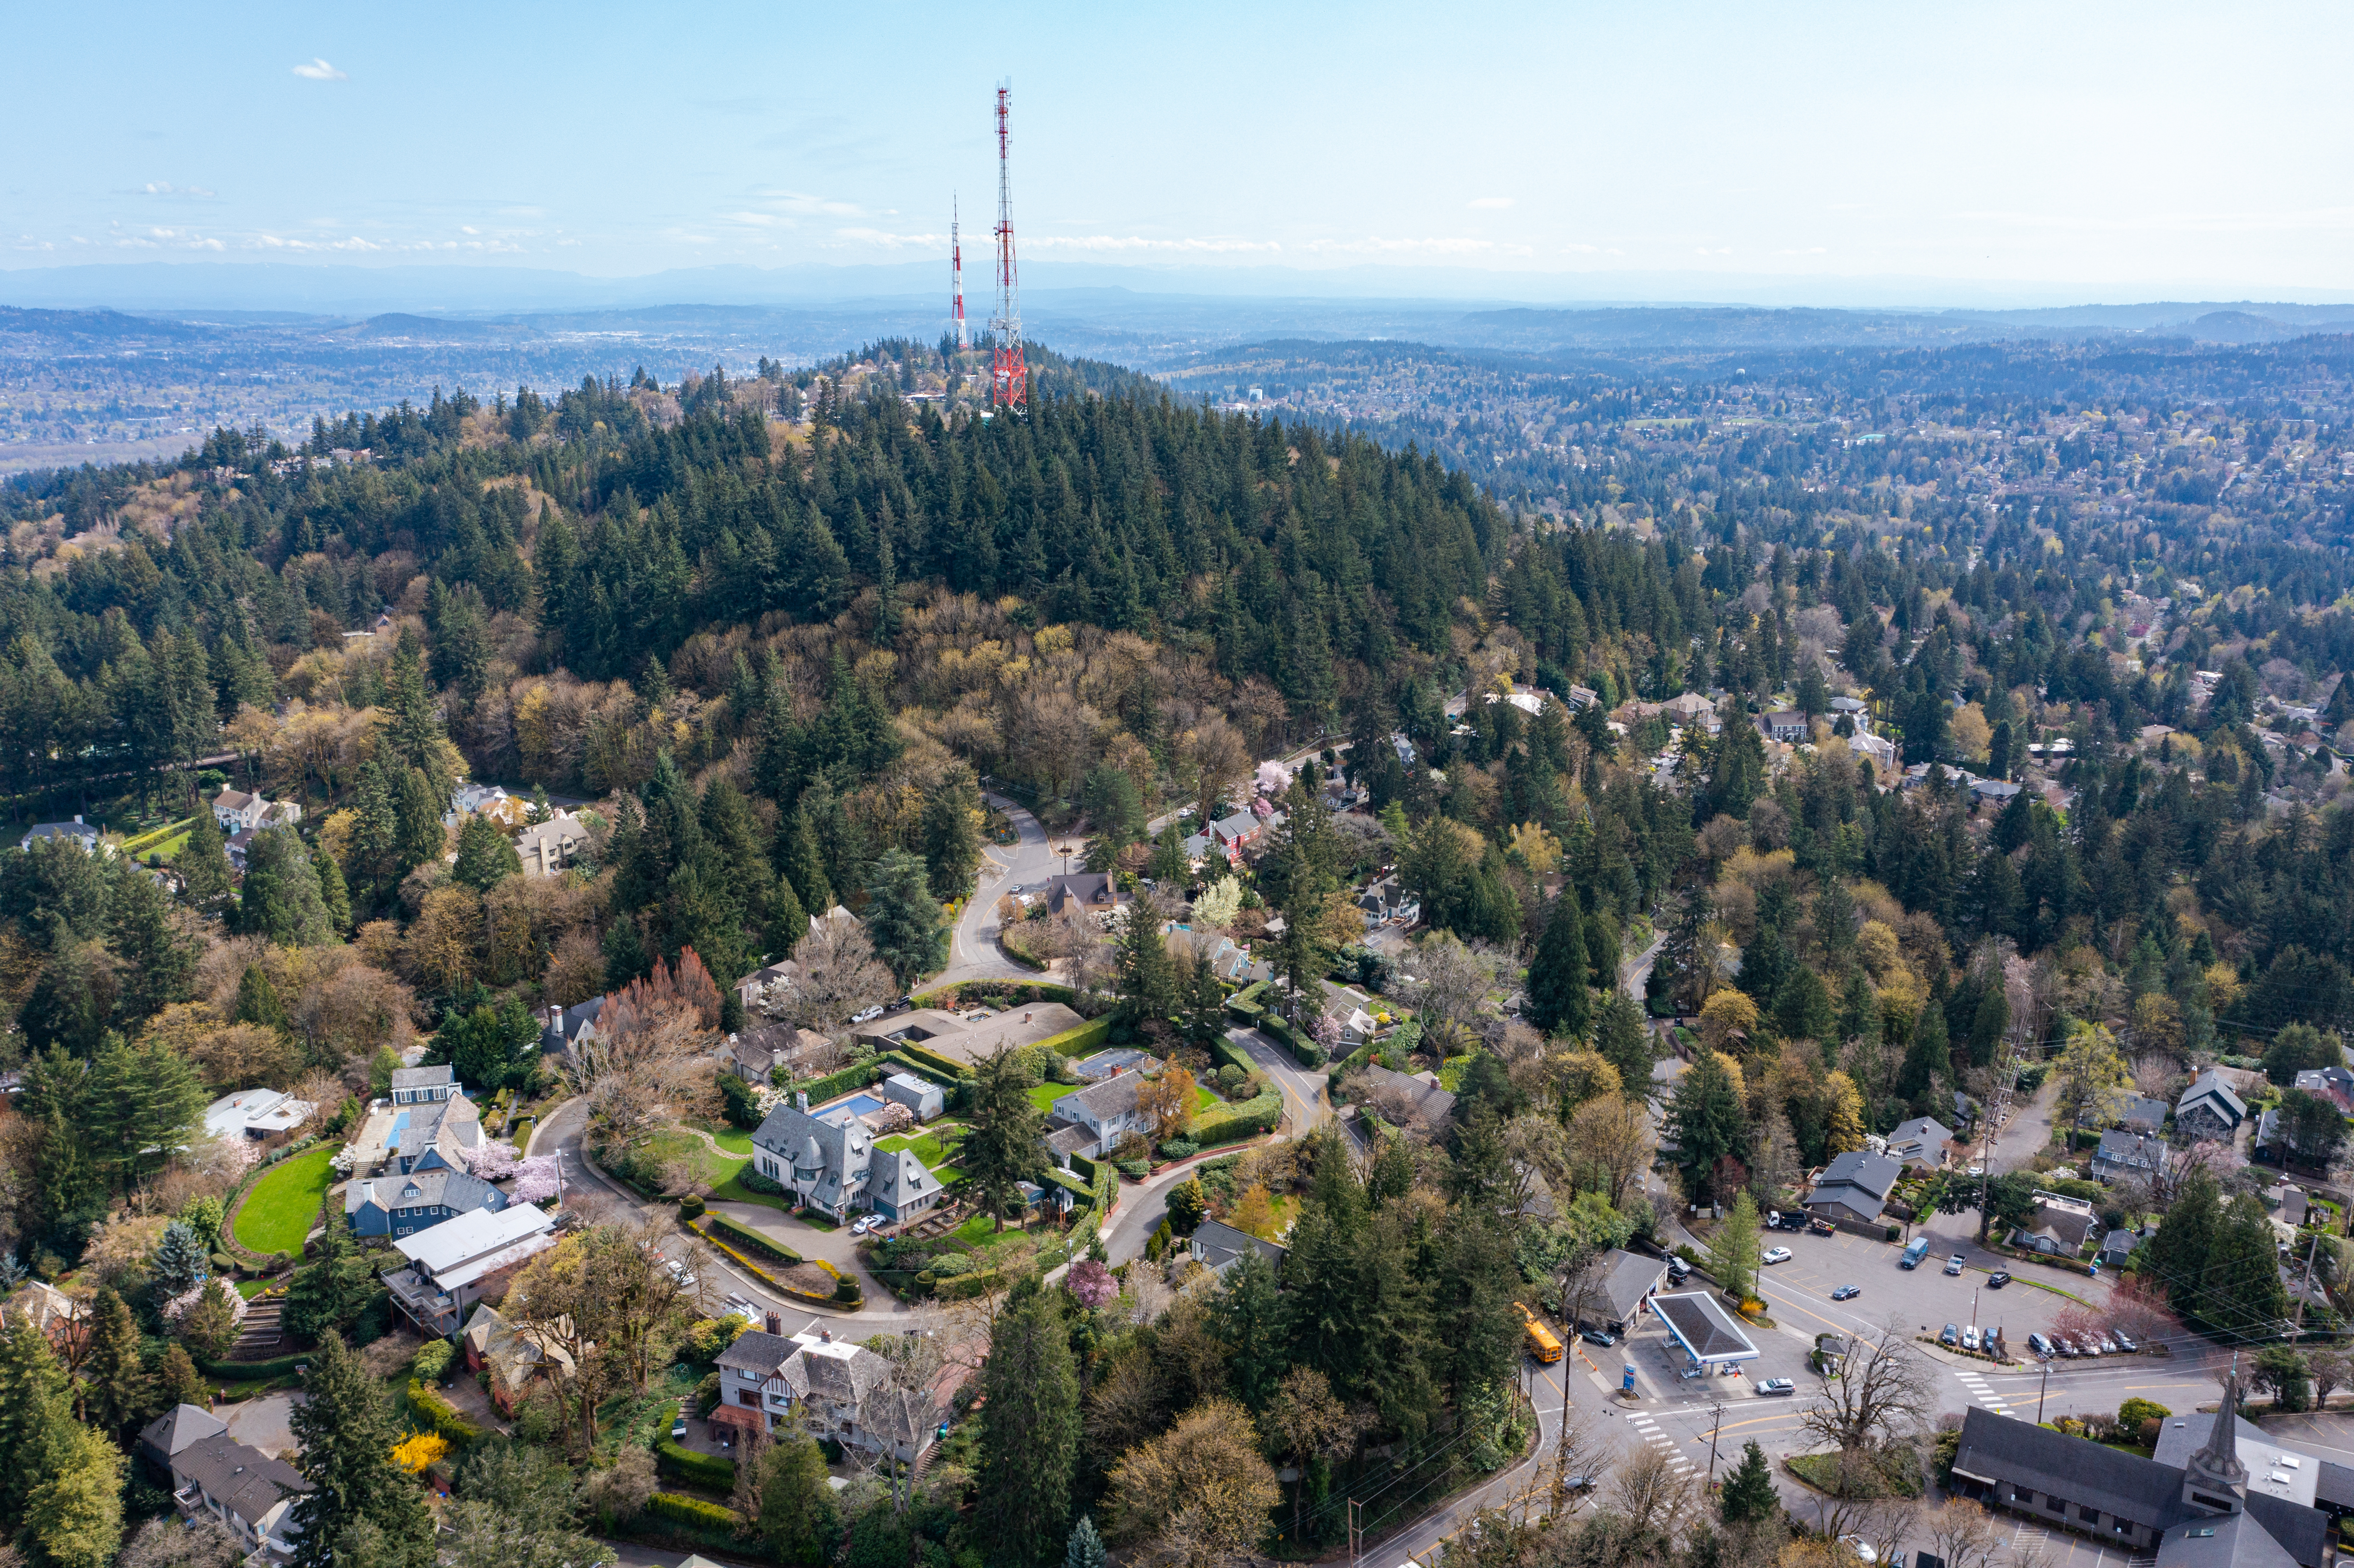
Denied by His Own Credit Union: How a Self-Employed Attorney Bought in Portland's Southwest Hills with a Bank Statement Loan
A Portland attorney had recently been depositing over $100,000 a month into his business account, but his credit union said his tax returns didn't show enough income. We ran a side-by-side income analysis before pulling credit, and a bank statement loan qualified him for more, at better 30-year fixed pricing.
All calculator results are estimates for informational purposes only and do not constitute a loan commitment or guarantee of any specific rate or terms. Actual loan terms will depend on creditworthiness, property type, and market conditions. Lumen Mortgage Corporation · NMLS #1498678 · Licensed in Oregon & California · 920 SW 6th Ave, Suite 1200, Portland, OR 97204.