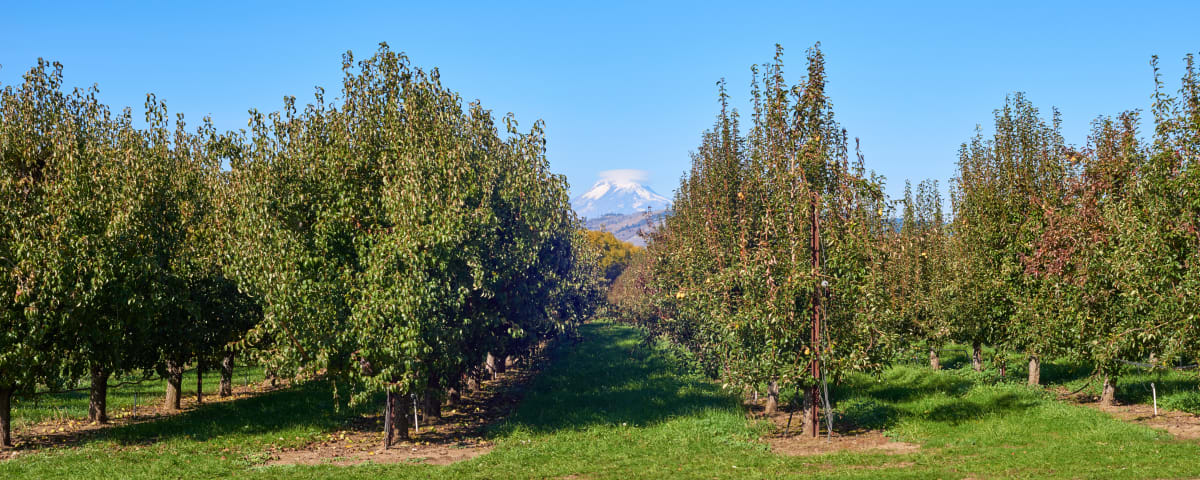
Can you get a 30-year fixed-rate loan on a farm or orchard?
Yes, but usually not from a commercial bank. Most banks fix farm real estate loans for only 3, 5 or 7 years, then reprice them off an index like the 5-year Treasury, FHLB rates or Prime, often with a 5-year balloon and a step-down prepayment penalty. In this case study, a Hood River orchard owner whose orchard is also his home refinanced his $1.65M bank loan into a true 30-year fixed ag loan with no prepayment penalty and took out an additional $250,000 for working capital and improvements. It closed in 5 weeks.
Best for: Orchard, vineyard, ranch and farm owners in Oregon and California who want a payment that never changes
At the end of summer, an orchard owner in Hood River reached out to us. His orchard is also his home, and he was tired of his bank's loan terms: a variable rate, a prepayment penalty, and a loan structure that pushed him back to the table every few years. He asked a simple question: could he get a fixed rate? Five weeks later he had a true 30-year fixed-rate ag loan, $250,000 in working capital, and a payment that will never change.
Why Bank Ag Loans Keep You Refinancing
At commercial banks, ag lending usually splits into three buckets, and the terms differ quite a bit between them. Farm real estate loans, the bucket that covers an orchard and the home on it, tend to follow the same pattern: - Rate structure: Banks generally won't fund long fixed-rate ag loans on their own balance sheet. The most common structure is "fixed for a period," typically 3, 5 or 7 years. The loan then reprices off a Treasury index (often the 5-year CMT), FHLB advance rates, or WSJ Prime plus a margin. Fully variable loans tied to Prime are also common, especially at smaller community banks. - Amortization: 20 to 25 years is the norm. Some banks go to 30 on strong deals, and some cap at 15 to 20 on riskier collateral. - Balloon: A 5-year balloon on a 20- or 25-year amortization is very typical. - Payments: Annual or semiannual payments timed to harvest or livestock sales are standard, though monthly is fine for borrowers with off-farm or steady income. - LTV and prepayment: LTV typically runs 60 to 70%. A step-down prepayment penalty during the fixed period is common. Put those together and you get a cycle. The rate resets or the balloon comes due, you refinance, and a new prepayment penalty starts. Your payment depends on where rates happen to be every few years, which makes it hard to plan a business that already rides on weather and crop prices.
What He Wanted: Stability
When we talked, his priority was clear. He wanted long-term stability, and only fixed-rate financing could give him that. He also wanted to pull out some equity for working capital and improvements to the property, and he didn't want a new prepayment penalty locking him in.
How We Structured It: A True 30-Year Fixed Ag Loan
We structured a true 30-year fixed-rate agricultural loan: fixed for the full term, fully amortizing, with no balloon. The loan: - Paid off his existing $1,650,000 bank loan - Added $250,000 cash out for working capital and property improvements - Has no prepayment penalty, so if rates drop he can refinance any time without paying to leave - Has a payment that never changes until the loan is paid off You can model your own fixed-rate scenario, including payment frequency, in our agricultural loan calculator.
Typical bank farm real estate loan vs. his new loan
Hood River orchard and home: $1,650,000 payoff plus $250,000 cash out
| Typical bank ag loan | 30-year fixed ag loan (his choice) | |
|---|---|---|
| Rate | Fixed 3, 5 or 7 years, then reprices off Treasury, FHLB or Prime; or fully variable | Fixed for all 30 years |
| Amortization | Usually 20 to 25 years | 30 years, fully amortizing |
| Balloon | 5-year balloon is common | None |
| Prepayment penalty | Step-down penalty during the fixed period is common | None |
| Typical LTV | 60 to 70% | Based on property and program |
| Payment | Can change at each reset | Never changes |
| Cash out in this case | — | $250,000 for working capital and improvements |
Closed in 5 Weeks
Five weeks after his first call, he had working capital in hand and a fixed-rate loan with a payment he can count on. Taking the variability out meant he and his family can plan around a payment they know will never change. And if rates come down, he's free to take advantage of it.
Is a Fixed-Rate Ag Loan Right for You?
A long-term fixed rate makes the most sense when your operation and your home are tied to the same property and you plan to stay. It also fits when your bank loan has a reset or balloon coming up, or when you want to pull out equity without starting a new prepayment penalty. If you farm in the Columbia Gorge or elsewhere in the state, see our Oregon agricultural loans for programs and requirements, or read more about Hood River and Gorge financing.
Model Your Farm Loan
Agricultural Loan Calculator
Agricultural loans work differently from residential mortgages — larger required down payments, sometimes shorter amortization periods, and monthly carrying costs that need to work against seasonal income rather than a steady paycheck. Before you make an offer on farmland or a rural property, knowing your payment scenario shapes the entire negotiation.
The ag loan calculator lets you model purchase price against the 25–35% down payments typical of farm lending, compare 20-, 25-, and 30-year amortization schedules, and see how rate variations move your monthly carrying cost. For a cash-flowing operation, that monthly number is as important as the land price itself.
Down payment scenarios
Model your monthly payment at 25%, 30%, and 35% down — the range most ag lenders require on farm purchases.
Amortization comparison
See how 20-yr vs. 25-yr vs. 30-yr amortization changes your monthly payment and total interest paid over time.
Rate sensitivity
Small rate differences compound significantly over long amortizations on large balances. See the real magnitude.
Free · No login · No credit pull required
Frequently Asked Questions
Why don't banks offer 30-year fixed ag loans?
Can I get a fixed-rate loan on an orchard that's also my home?
Can I take cash out when I refinance a farm loan?
Is there a prepayment penalty?
How long does an ag refinance take?
Looking for Ag Financing?
Farm purchase, ranch, raw land, operating lines, and specialty crop loans — structured around how your operation actually works.
Bottom Line
We love working with farmers and the ag community. If your bank loan has you on a refinance cycle, a fixed-rate ag loan with no prepayment penalty can give your family a payment you can plan around for good. Run your numbers in the agricultural loan calculator, then call Lumen Mortgage at 503-966-9255 or email dblackmon@lumenmortgage.com. Licensed in Oregon and California. NMLS #1498678.

