Can a veteran with a 100% VA disability rating buy a $995K home in Orange County with a VA loan?
Yes. Veterans who receive VA disability compensation are exempt from the VA funding fee, and because disability pay is tax-free it can be grossed up for qualifying. In this case study, a recently separated veteran and his wife relocated from Washington and bought a $995,000 home in Rancho Santa Margarita. We qualified them on his grossed-up disability income and both of their base wages, without counting any new commission or self-employment income.
Best for: Veterans relocating to Orange County, especially those with VA disability income or a new job
Moving across state lines is stressful enough without wondering whether your mortgage will hold up. This family came to us from Washington after he finished more than 10 years of military service. Both of them were starting new jobs, they had just sold their home, and they wanted to land somewhere sunny in Orange County. Here's how we put the loan together, and why the simplest qualifying path turned out to be the best one.
The Situation: New State, New Jobs, Same Goal
Him: a veteran fresh out of the military after more than 10 years of service, with a 100% VA disability rating. He had just started a sales job at a tech company, paid as base salary plus commission. Her: she had just moved into a sales job too. Before that she was self-employed and earned strong income, but only for about the last year. The money: $240,000 from the sale of their home in Washington to put down. The goal: a home in a great Orange County neighborhood, pre-approved before they started touring so they could shop with confidence.
Why the VA Funding Fee Was Waived
Most VA borrowers pay a one-time funding fee, usually financed into the loan. Veterans who receive VA compensation for a service-connected disability are exempt. With a 100% rating he qualified for the exemption. With 10% or more down, the fee would have been 1.25% of the loan, or about $9,440 on their $755,000 loan, so the exemption kept that off their balance from day one. VA loans also have no monthly mortgage insurance, and with full entitlement there's no VA loan limit. That matters in Orange County, where many homes sit near or above the conforming limit. You can model your own payment with our VA loan calculator.
Grossing Up Tax-Free Disability Income
VA disability compensation isn't taxed, so a dollar of disability pay goes further than a dollar of taxable wages. Underwriting guidelines account for that by letting us gross up non-taxable income for qualifying, often by 25%. That raises the income used in the debt-to-income ratio without changing what actually lands in his account. For this family, the gross-up on his disability income was a big part of why we didn't need to count any of their newer, less-established income. It's also stable: a 100% rating is long-term income, which underwriters like.
Base Wage Only: Leaving Commission and Self-Employment on the Table
New commission income usually needs a track record before it can count, and both of them were new to their sales roles. So we qualified each of them on their base wage only. Any commissions they earn are upside, not something the payment depends on. Her self-employment history was the interesting part. She'd had a strong year, and we could have used our 12-month bank statement loan or our one-year self-employed program to count all of it. But those are non-QM options, and the VA loan priced better. Once we knew his grossed-up disability income plus both base wages was enough, there was no reason to pay more for income they didn't need. That's the point of comparing every path at pre-approval: sometimes the best loan is the one that uses the least of your income. If you are self-employed and want to see what a bank statement loan could do for you, try our bank statement loan calculator.
Pre-Approved, Then Off to Rancho Santa Margarita
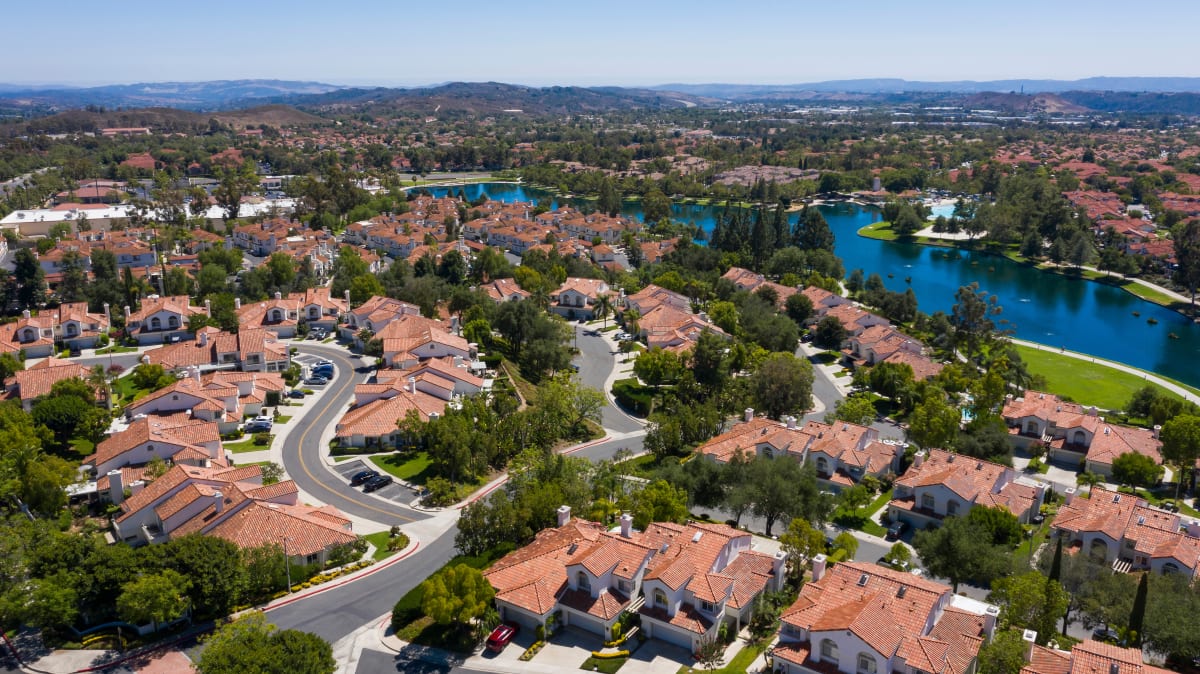
With a full pre-approval in hand, they went shopping and found the right fit: a home in a great neighborhood in Rancho Santa Margarita for $995,000, just under $1 million. They put $240,000 from their Washington sale down (about 24%), bringing the loan to $755,000 and lowering the monthly payment. From rain and clouds to sunny and dry. It was our pleasure helping this family relocate from Washington to Orange County. See our Orange County mortgage guide for local loan limits and home values.
Relocating to California? Plan for These Differences
- State income tax. Washington has no state income tax; California does. Factor it into your budget, even though it doesn't change how the loan is underwritten. - Property taxes. California property tax is generally based on your purchase price, plus any local assessments such as Mello-Roos in newer South County communities. Ask for the full tax bill on any home you're considering. - Homeowners insurance. Get quotes early, especially in areas near open space. - Timing a sale and purchase. If your down payment is tied up in a home you haven't sold yet, a bridge loan can help you buy first.
Calculate Your VA Benefit
VA Loan & Entitlement Calculator
Entitlement is the most misunderstood concept in the VA loan program — and that confusion leads veterans to believe they can't purchase when they actually can. The VA Entitlement Calculator demystifies the math: full vs. partial entitlement, what your remaining entitlement is after a prior VA loan, and whether a down payment will be required on your next purchase.
The calculator also computes your VA Funding Fee at every down payment tier — and applies the disability exemption for veterans with a 10%+ service-connected rating. That exemption alone is worth more than $12,000 on a $600,000 purchase. It's not a detail to overlook.
Full vs. partial entitlement
Understand how a prior VA loan affects your current buying power and available guarantee amount.
Zero-down maximum
Calculate the largest loan you can take with no down payment using your current entitlement.
Funding fee + disability toggle
See your exact funding fee at any down payment tier — and apply the exemption if you have a service-connected rating.
Free · No login · No credit pull required
Frequently Asked Questions
Do veterans with a VA disability rating pay the VA funding fee?
Can VA disability income be grossed up to qualify for a mortgage?
Can I get a mortgage right after starting a new commission sales job?
Can I buy a home with only one year of self-employment?
Is there a VA loan limit in Orange County?
Run Your VA Loan Numbers
Use our VA Entitlement & Funding Fee Calculator to see your max zero-down loan, required down payment, and exact funding fee — including the disability exemption.
Bottom Line
Every relocation is different, but the approach is the same: line up every qualifying option before you shop, then choose the one that costs the least. For this family, that meant a VA loan with no funding fee, tax-free disability income grossed up, and base wages only. If you are a veteran moving to Orange County, start with a VA pre-approval or email us your scenario.